 YouTube
 Spotify
 Amazon
 iHeart
 Apple
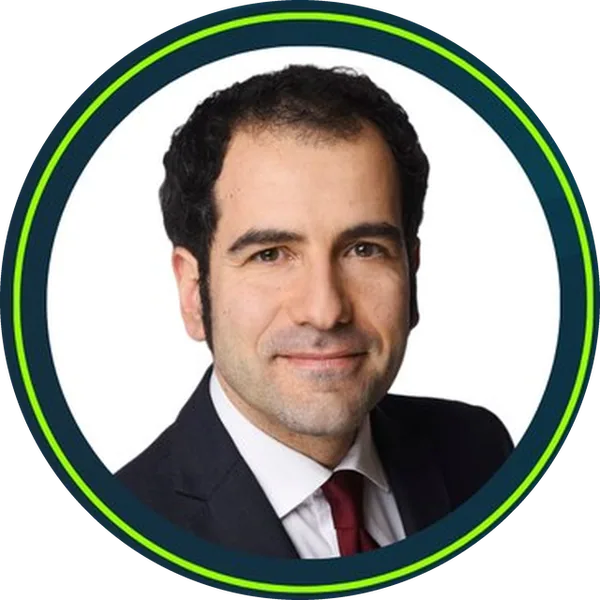
Danilo Raponi
The Group Head of Innovation at Generali joins James Benham at InsurTech Insights London 2026 to dissect what large insurers consistently misunderstand about innovation, from a blockchain consortium that collapsed in plain sight to the discovery frameworks that surface real problems, and why humanoid robots are a five-year industry reckoning, not a twenty-year one.
The full episode
The whole conversation, recorded live at InsurTech Insights London 2026. Blockchain post-mortems, the three questions that surface a real problem, and why robotics is a five-year reckoning.
The Failure Pattern Nobody Talks About
Insurance innovation conferences run on a predictable cycle: major announcements, press releases, consortium formations, then silence. Raponi calls this the "Keyser Söze pattern": innovation projects that vanish without a post-mortem, without acknowledgment, without a lesson shared.
He inherited one firsthand at Generali: a blockchain-based art insurance platform joining forces with a major bank, a stock exchange, and an auction house. The technology premise seemed sound. The problem was everything else: no confirmed client demand, and no explicit alignment on what each partner actually wanted out of the project.
"Start with the problem, not the solution. That is the fundamental rule."
Danilo Raponi, Group Head of Innovation, Generali
When the consortium needed to scale, the diverging objectives (insurance sales expansion, lending volume, transaction fees) surfaced as irreconcilable. The project collapsed. The lesson isn't that blockchain failed. It's that the project never confirmed a real problem existed before building anything.
Insurance Companies Are Not Tech Companies
Carriers attempting to become technology companies dilute their core competency without gaining genuine competitive edge. Insurance firms already face enormous complexity in pricing risk, managing risk transfer, and optimizing float returns: that's a full-time job.
Rather than building internally, Raponi recommends partnering with specialized firms that already excel in a given area. The Florida property market makes the cost of ignoring this concrete: insurers that expanded without fully modeling litigation exposure alongside hurricane risk faced catastrophic losses when claim payouts exceeded every pricing assumption.
His discipline at Generali: fund two experiments thoroughly rather than run one hundred poorly. Focus is the differentiator, a truth that applies at every scale, from early-stage startup to global carrier.
The Magic Wand Question
The primary failure mode in insurance innovation is building solutions before confirming that a real customer problem exists. Insurtechs present impressive demos at conferences, collect polite interest, then return months later seeking six-figure contracts, only to find there was never a real buyer.
Raponi's three-question discovery framework cuts through the noise:
"If you'd wave a magic wand and change one thing, what would you change? That's when you'll actually get truth."
Danilo Raponi
The third question only works after the first two have built rapport: early questions yield polished, defensive answers. Later questions, after the relationship has warmed, reveal genuine struggles. Generali's 15-person innovation team, plus 30 embedded colleagues, runs this framework across geographies: France's pain points differ from the UK's, and that difference matters.
Robotics Is a Five-Year Problem
Beyond large language models (which Raponi characterizes as "now, not the future"), robotics represents the next major disruption. He predicts humanoid robots will become commonplace within five to ten years, not the twenty-to-thirty-year horizon most insurance scenario planners are working with.
The industry underestimates the systemic breadth. Robot-caused injuries create obvious liability questions. But the deeper changes run further: workers' compensation underwriting assumptions, property insurance frameworks, and life and disability coverage models all require fundamental reconsideration when robots become everyday environmental infrastructure.
China's manufacturing investments and Tesla's Optimus program signal that adoption speed will far outpace the industry's planning timelines. Raponi disclosed being an early-stage investor in a serious robotics company, and warns the first significant developments arrive within two years, not ten.
Key Takeaways
Technology-first innovation fails when it skips confirming real problems exist. Build a hypothesis around a genuine pain point before touching a solution.
Two well-funded experiments beat one hundred underfunded ones. The principle that defines startup success applies equally to global carriers.
Multi-party projects collapse when partner objectives diverge during scaling. Surface and resolve misalignment explicitly before any money moves.
Industry planning assumptions underestimate humanoid robot adoption speed by roughly two decades. Systemic business model impacts extend far beyond obvious liability questions.