 YouTube
 Spotify
 Amazon
 iHeart
 Apple
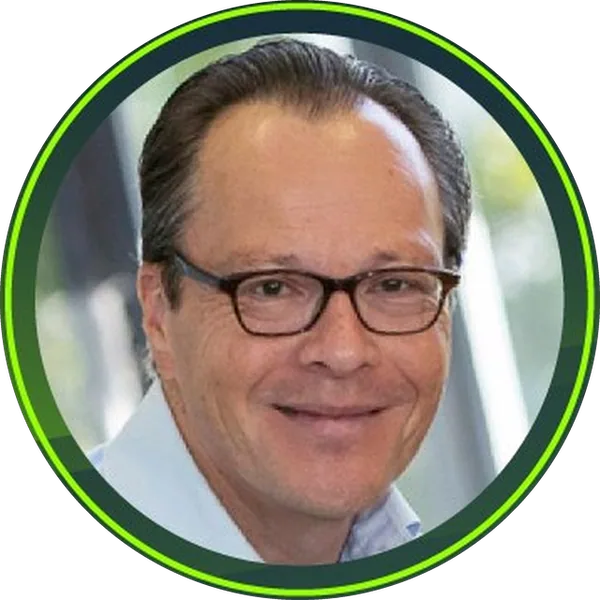
Hanno Mijer
Hanno Mijer shares his expertise and insights on building insurance companies from within. Learn tips and tricks on leveraging innovation to drive growth and tackling the key challenges and opportunities that lie ahead.
In this episode, our hosts James Benham and Rob Galbraith interview Hanno Mijer who's been involved with many of the biggest insurance companies in the world and now, does consulting for technology implementation, sales and marketing.
Hanno Mijer graduated college as an actuary, but his passion for building businesses was evident early in his life. Hanno realized early in his career that his passion was around marketing and business development.
The full episode
Press play for the whole conversation.

Looking ahead to the future of the industry
With his years of experience, Hanno has a panoramic view of where insurtech came from and where insurtech is right now. He states that "technology was always there and played an important role" but now companies have the ability to harness data, gather data and leverage it into improvements for products and services in the insurance industry.
"Technology is accelerating all the time, right? If it's around digitizing the claims process or if it's about using AI to really leverage sophisticated models and translate it into insights which people understand, it has always been there. But what I find very encouraging is that technology wasn't really on the radar screen of leadership at all. Now, they're moving a little bit more from an operational perspective. They ask how technology could help processes become more effective."
Hanno thinks that technology is more than ever, a vital part of what the industry tries to achieve to make life easier for customers and stakeholders. Not only in terms of better positioning but also of better value and to provide insights based on data.
According to Hanno, the industry still has a long way to go.
"There was an article in the Financial Times about how difficult it is for people to ensure their homes in New York or Florida. It was referring to flooding and other climate driven changes and I have to say when I read that article I almost fell off my chair because basically it was saying 'It's extremely hard or sometimes impossible to get appropriate or affordable insurance. I was flabbergasted because the technology is there, there are sensors, there are models, there is data and particularly the hope that AI makes it possible for carriers to be much more accurate about the underwriting in the pricing and make it available to customers."
He questions why, while having the available technology, that there are hundreds of thousands of people who cannot get appropriate insurance. For him, that means that as an industry, insurance still has to harness technology and the available data and put them into good use for their users.
The fluff vs the real stuff around technology
When asked about separating true revolutionary developments on tech for the insurance industry Hanno retaliates, "Do we really understand the underlying need of the end customer?". His bottom line is that insurance companies can do much more to help their clients become more resilient.
Hanno shared an example around climate change saying that in his last job, there was a lot of fluff. Initially, a number of climate scientists developed great climate models, analyses and diagrams. But that didn't do a lot by itself, so it was fluff. Nobody wanted to buy it, even internally. It was great to show in meetings but they didn't have a concrete application.
Hanno and his team realized that they could put this data to use to benefit customers.
Hanno highlights that "it's not only about the content but also how you can use it if that makes sense now".
At the same time, Hanno states that there are dozens and dozens of big multinational companies across Europe, but also in the US, who've actually incorporated insurtech services. This is because they realize it is the combination of the risk management philosophy of insurers and knowledge with technology that actually offers stuff which clients are happy to pay for. For Hanno, it's about strategic business.
"I think it is actually the result of a lot of incremental things you do, but but I want to refer to what you said because it really does start with the mindset, but that's linked to having a very clear understanding what you're trying to achieve".
From the conversation
"Pretty early on during my university I realized I was probably the worst actuary in the room but also probably one of the very few who was really interested more in the marketing sales business development side of the industry".
After graduating from college, he started developing client solutions for a dutch insurance company. After proving to be a valuable asset for the company, they quickly sent him abroad to central eastern Europe, and Asia, where he joined what is now called Willestow Watson, which was in those days called Watson Wide, very much a traditional actuarial firm.
After his experience with Watson Wide, he joined Zurich, the big global insurance company. They offered him to set up a new business. He got into the venture of opening successful branches of Zurich, like Zurich Global and Zurich Resilience Risk Consulting.
With years of experience in the industry, Hanno retired in early 2024, but continued to provide strategic consulting services for insurtech companies.
"To my surprise there were a lot of similarities between what I've done building insurance companies in an insurance company and now that I've joined a number of InsurTechs as an advisor and also working with private equity."
The full transcript
Transcribed automatically from the episode audio, so some names and terms may be misheard.
James BenhamOn this episode of the InsurTech Geek podcast, we're talking about building insurance companies from within with Hanno Mijer, InsurTech advisor and former founding CEO of multiple global insurance businesses. The InsurTech Geek Podcast is all about technology that's transforming and disrupting the insurance world. We'll be interviewing guests and doing deep dives into specific tech we see changing the industry. We're taking you on a journey through insurance tech, so enjoy the ride and geek out. Terra, our sponsor for this week's episode, is driving innovation and management of insurance claims and policies.
Discover how Terra empowers insurers with benchmarking tools, claims management and policy administration, and an ancillary services marketplace at terra.insure. And we are back with another great episode of the InsurTech Geek podcast. I'm your host, James Benham. With me, my illustrious cohost, Rob Galbraith. Rob, how are you doing?
Rob GalbraithDoing well, James. Doing well. How are doing?
James BenhamOutstanding. It's been a good good week, good weekend, and I'm ready to tackle another week of building insurance software and, you know, building claims and policy admin systems and tackling Froy's and Troy's and doing regulatory filings and all the all the fantastic things you have to do when you're in the insurance business. I'm ready for it. I'm excited and know fired up and going nuts every minute as we as we say around here. Are things over in San Antonio?
Rob GalbraithYeah, human. It's funny. My daughter this morning, you know, she was kind of saying she's like, why am I so hot? And I was like, well, hey, you know, it's spring. It's getting warmer. I was like, but be, you know, we had a bunch of rain showers and thunderstorms come through. And so I said, you know, fortunately in San Antonio, it's not quite Houston or Louisiana or Florida or any place like that. But I was like, yes, that is what you're sensing humidity. So yeah, she's trying to understand why her hair is not cooperating and all that good stuff.
I hate I tell you Explain what the weather to her. It it
James BenhamThe heat is on, man. I mean, we get like two or three weeks of spring and then it's straight into hot and humid and the same thing in College Station, a lot of rain. I am getting ready though. As we record this, Monday, April 29. I'm getting ready for REMS in a week. And so I'm going be out in San Diego for the Risk Management Society's annual gathering. Of course, San Diego is 72 and sunny every day. So I'm looking forward to that. But I'm also looking forward to seeing all of my friends, colleagues, clients, prospects, everybody kind of gathers once a year for the, I would say probably the world's largest insurance conference every year.
I think REMS definitely qualifies as that. So I'm super excited to see that. I kind of view REMS as a giant reunion. With us from Switzerland, from Zurich
Hanno Mijeris Hanno Mijer. Hanno, how are you doing? I'm doing great. I love your effort to speak a little bit about the German accent, James. Good for you. Sprechenze Deutsche. Okay. But it is funny that in your interview, you've been getting ready for Rinse. I've been there many, many times. I completely concur with you. It's a great event. And actually, Rob, I guess you're in San Antonio. The last time I visited Rinse was few years ago. I was actually in San Antonio. Saw the LMO. It was fantastic.
Really cool. So, yeah. Well, have fun, James. I'm sure you're going to have fun.
James BenhamOh, yeah. Yeah. Well, you know, RIMS is like, I'll be exhibiting Terra, my REMS system, the claims and policy admin system. So I'll be exhibiting that in a booth. But the real action at REMS starts at five p. M. And goes until about two to three to 4AM every night.
Hanno MijerThat's when all
James Benhamthe receptions and gatherings and social events are. And so I'm excited to see all my friends there. I'm glad that you're familiar with it. And San Antonio is a really fun city. It's, it's got a lot of, really cool historical places. So I'm glad you got to go. I was at that rim. So you and I might have even shaken hands and don't even know it. So, Well, we might. We might. And actually, I think I've been at least once in San Diego for ribs as well.
So it was probably even earlier. Can't remember. I can't remember this hotel in the Riverside.
Hanno MijerThere's all these, you know, US Navy ships. It was just great, great venue to run as well. Oh, yeah. Yeah. Yeah. Well, they they
James Benhamthey pick they pick great, great cities. So we're going to chat about technology. We're going to chat about insurance and we're to go from there. But before we do, we're going to start about chatting about You know, I want to hear from you. Obviously, you're in Switzerland now. But where were you born and raised? And what did you want to be when you were a kid? Like, what did you grow up envisioning you were going to do?
Hanno MijerAll right. Well, you know, James, I was born in in The Netherlands long time ago. As long as I can remember, as any proper Dutch guy, I wanted to become a professional football player. Yeah. And for you guys, being American, that's that's actually. Yeah. But, yeah, but, know, as it happened, I I I ended up getting a master's actuarial science and then started building business insurance the rest of my life, which was almost as exciting as being a professional football player, I have to say. It was fun.
It was fun. Yeah. That's that's really great.
James BenhamOh, look. I now I grew up, just so you know, just so this is clear, I grew up playing soccer, football.
Hanno MijerSo I so my whole You're American. You're American. How's it possible?
James BenhamWell, because my my mom wouldn't let me play American football because she was worried about head injuries in the early eighties, which was very ahead of its time. And I grew up traveling to Mexico as a child, like every year and got to play soccer with just some incredibly talented people down there. And so, and then my, when I was a kid, I went to this summer soccer camp run by a couple of Brit British guys who were absolutely insane. And they, they taught me how to play real, real British, real, real British football.
And so I I love playing. I was a goalkeeper my whole life. And and then when I turned when I got into my twenties, I switched into a a right defensive back because I got tired of being the last the last man standing. So so I can appreciate that. I'll I'll say, look, Major League Soccer is much more popular here now than it ever was. Yeah.
Hanno MijerYeah. Yeah. Yeah. Well, good stuff. Good stuff. Good stuff. So what'd
James Benhamyou go to college for? What did you study and what did you end up going into? Right, okay. So I did actually
Hanno Mijerwent to college, did agronomics and then enrolled it into a master's of actuarial science. So I'm by education, I'm an actuary. But I have to say that pretty early on during my university day, I realized I was probably the worst actuary in the room, but also probably one of the very few who was really interested more in the marketing, sales, business development side of the industry. And I'm not really sure who's going to see this podcast, so I don't want to insult anyone, but I also realized I was probably the worst mathematician in the room, but probably a bit better in communication than most others.
So I thought maybe I could combine that into a career. And actually, that's what really happened. You know, when I went out, I was when I was graduating, the the a couple of restaurants companies who actually thought that somebody who understood the basics of insurance, the actuarial technical part, but also was really passionate about building businesses, developing new client solutions would be an interesting prospect for them. And that's actually my life in a nutshell because I started doing a core induction insurance company, but then they sent me quickly abroad, abroad to Central And Eastern Europe, to Asia Pacific.
Then I joined what is now called Willis Towers Watson, which was in those days called Watson White, very much a traditional actuarial firm. And actually, again, dare I say it, I joined them in London. I was very much the old one out. I was about the only non English or US partner. More importantly, I was the only one actually selling Medevo to Medevo they were developing. And it was great one. Now almost twenty years ago, and that's why I'm living in Zurich, I joined Zurich, the big global insurance company, and I was asked every single time when they wanted to when they, I mean, when Mario Greco, the Zurich CEO, wanted to set up a new business.
He already asked me to do that, and I did. And I did that on on on on every side of every line of business you can you can think of. Right? I built a big global ventures business from almost nothing to a multibillion dollar business. I built Zurich's global travel business, which actually was headquartered in Sydney, which is fantastic, so I happened to live a few years there. And the last three years, I built from scratch Zurich's resilience risk consulting business, which actually I'm pretty pleased to say and proud that my team was the fastest growing business of Zurich, or one of the fastest growing business of Zurich three years in a row.
So, yep, story in nutshell. Four kids, three boys. They all love soccer like we're discussing earlier, all sporting my home tea, although they never lived in Netherlands. So, pretty cool. And I retired a few months ago and found to my maybe a bit to my surprise that there was a lot of similarities between what I've done building insurance companies in an insurance company and now that I've joined a number of insure techs as an advisor and also worked with private equity, realized that a lot of the skills I've learned are actually very applicable in the inter tech space.
And maybe even more building this bridge because James, mentioned you representing your own company in San maybe maybe or maybe not. One of the judge you face is that you you think you probably have the best company in its sort in the world. Why don't insurance companies not understand that? If they understand, how can we make it work more together. And I think that crossroads is where I'm having a lot of fun at this point in time. So, you know, maybe a bit of a long introduction, but you you wanted to know This who I is who I am.
And
James Benhamfind it, you know, you've gotten to work on multiple sides of the business, right? Not just on the brokerage side or the carrier side. You've gotten to really work, work through. That's, that's kind of rare people trying to tend to stay in one lane in insurance. And now you've retired and obviously you're a InsurTech advisor and mentor counselor. You're doing some really cool things. And we're going to talk about that, but it's good to know how you got there. Rob, what you got?
Rob GalbraithYeah. I know. Thank you so much for walking us through your background. It's great to have you on the podcast. So I I would just love kind of a broad perspective from you of, you know, based on your experience and now kinda looking ahead, you've seen a ton of technological change. You've seen the, you know, introduction and refinement and evolution of artificial intelligence, particular over the last, you know, ten ten ten years or so. And, you know, generative AI has been the big buzz for the last year or so.
So just curious, you know, working for traditional firms, starting up new lines of business, and now working with startups. You know, how has your view on the role of technology within the industry evolved over time? You
Hanno Mijerknow, I'm I'm technology, I mean, obviously, now we we so much key of everything we do. But I I like to think looking backwards, maybe without even realizing it, technology was always there and play an important part. And, you know, when I when I go back to the early days of of my career, I mean, mean, we hardly used spreadsheets or PowerPoint or Excel, which was then, you know, CSD, SDSD. The new frontier are which is quite far away from where we are today when we have learned how to harness data, gather data, turn it into insights, into learnings.
Then of course, the last, like you said, ten years, maybe accelerating now, how the industry starts using AI. And and what I maybe slightly different angle. What I would like to think is that technology is is is accelerating all the time. Right? If if it's around digitizing the claims process, if it's about using AI to really leverage sophisticated models and translate it into insights which people actually understand has always been there. What I find very encouraging is that where technology in the past was really either not on the radar screen of leadership at all, then moved it a little bit more, more so from an operational perspective, how it could help process more effective.
I think now technology is more than ever part of what the industry tries to achieve to make life easier for customers, for stakeholders, not only in terms of better positioning, better value, but also really to make those insights available. At the same time, I think the industry has still a long way to go there. I have to say that I'm not sure you read it, but yesterday or in the weekend, there was an article in the Financial Times about how how how difficult it is for for people to insure their homes in in New York or Florida.
I was referring to flooding and other climate driven different changes. And I have to say, when I read that article, you may wanna you may you may wanna look at it, I fell off my chair because basically, it was saying, well, you know, when you as a you know, we are an average person, extremely hard, sometimes impossible to get appropriate or affordable insurance. And then they quoted some some senior jury not jury, some some senior industry leaders who were saying, oh, it's extreme, but we can't do it, and the technology is not there, and poor people, we're not going to solve this.
I was flab against it because it also showed, because the technology, as you guys know, is there. There sensors, there are models, there data, particularly with the whole AI. It is extremely well possible for carriers to be much more accurate about their underwriting, the pricing, make it available to customers. So how come that there are thousands, 10,000, 100,000 people cannot get appropriate assurance? That actually means as an industry, I think we still have a way to go to harness the technology, to harness the available data.
And actually, this is I find myself dealing with this on a different level every single day. When I said earlier that I can see a lot of the lessons I've learned when building insurance companies from within, it's also about how do you bring together people who come from completely different perspective. In this case, how do you bring together maybe traditional thinking insurance executives with the technology which the Intritex or other firms are developing, and then making sure that it's being melded together to benefit the customer, being it a homeowner in Florida or be it a a company like IKEA or Audi dealing with climate change in in Europe.
For me, that is a theme which for me is at the heart of the technology discussion. Is yes. It's fantastic. And and, yeah, and people like you are in the midst of this will probably when given the floor you can talk for hours about all the benefits. But then the thing is, how in the end do we make sure as the industry, carriers, brokers, inter techs, what have you, to make this accessible and usable for the customer, whoever it is and whatever they may be, if that makes sense.
Rob GalbraithAbsolutely. Big science. Absolutely. And as you were talking, Hanu, I mean, I think about this is something I've talked about. I talked about my book, the end of insurance. If you know it, I've talked about in keynotes and I feel like I'm talking about it more and more five years since the publication of the book is availability and affordability. You know, have we still figured out those two issues? I mean, they get a lot of ink, they get a lot of press, they get a lot of conversations at conferences.
Yeah. But yet fundamentally, it just feels like it's tying back to that and you kind of wonder, you know, exciting as I am to see the growth of insurance markets and developing nations that don't necessarily have the robust history of a North America, of a Europe, at the same time, some of the more advanced economies are actually seeing almost like a retrenchment of the market where it's actually becoming more difficult. We've almost taken for granted in the past that insurance products would be there and be there at affordable rate where it's just an expense, not the major expense or prohibiting investment in other parts of your home or your business.
Hanno MijerYeah. Well actually I can't remember which one, but in one of your books you have some of these cases and I was just really wondering. It's so obvious when you explain what you have done with some of those companies and why is this not more widely spread? Why are not more companies adopting these methods? Because the point is it's not rocket science, right? The technology may be, but the way you apply it, the way implement it in Kary is not rocket science. It's all about the soft factors, it's about mindset, it's about the infrastructure of the company.
Anyway, we can talk about this for a referee, I think, which is not what we have. I
James Benhamalmost feel like circling back on a comment you made at the beginning of your answer around the soaring insurance premiums in New York and Florida, because it ties in, Rob, with what you just said. We almost take for granted that insurance is going to be available and markets will be available. And certainly we're, I think we're circling back on the need for insurers of last resort, the critical role they play in allowing commerce and business and life to continue. I think sometimes we forget that, you know, forget why states backstop insurers a last resort.
But when you see citizens as the largest property carrier in Florida, you're like, oh yeah, this is why. Because when, markets go crazy, sometimes we need a backstop. That being said, I think it's important to not lie to ourselves about why many of these markets are so challenging. In all too many cases, it's litigation expense, it's trial attorneys, many of whom have become legislators and elected officials. Like in Florida, the Speaker of the House is a trial attorney. And for years he blocked insurance reform support his own industry.
The only way that Florida and you look, Texas has more miles of Gulf Coastline than Florida does. We have an incredibly massive coastline in Texas, and we have a lot of coastal exposure. We don't have nearly the issues that Florida has because we have much tighter laws around tort reform and legislative reform. So let's just make sure that we lay the blame promptly majority on the shoulders of trial attorneys who are busy pumping billions of dollars out of insurance companies and claiming to be for the policyholder.
But aside from that, you know, technology has allowed a lot of companies to clearly draw that causation and correlation, right? Cause a, you know, so just because two items are correlated doesn't mean there's causality. But I think that, you know, the prevalence of really good data systems helps us identify, you know, the trouble spots are and hopefully fix them insurance. Inside Whereas in particular around analysis of unstructured data, my question for you is what do you think is fluff in insurance tech right now? What's the fluff and what's the real stuff?
So separate from me the fluff and the real stuff. Is there's a, every, every insurance, and I go to a lot of insurance conferences, there's far too much conversation about AI. It's oversaturated as a topic now, but it's, it's what you have to do to, to get, to get, get on the speaker docket right now. But there's a lot of conversation around AI, but, most insurance companies still struggle with basic adoption of core systems and eliminating Excel spreadsheets. So
Hanno Mijerwhat's the fluff and what's the real stuff? You know, I mean, the short answer really is that everything which cannot be put into a proposition or a service that you can actually sell is probably fluff. Right? Because I think what's a lot a lot there's a lot of, you know, waffling around around about technology and it's it's about to get academic and reach and it's about what it potentially could do. Everybody's talking about data lakes, etcetera. But in the end, I think the proof of the pudding is, okay, as an industry, as a carrier, do we really understand the underlying need of the end customer, be it be it the consumer in Florida or be it a big car company like Audi in in in Germany.
And then the technology which we have, either developed ourselves or our board or the data we have, can we put in something which makes sense? And maybe it's a slightly different angle to your question, but when you do that, you see remarkable results. And completely different than the topic we were talking about earlier is that what you see is that what insurance companies can do is much more about helping their clients become more resilient. Resilient for climate change, resilient for other other other other changing circumstances.
And, yeah, maybe I try to keep it very short, an an example. So around climate change in in in my last job, we realized as Jurek that we had a lot of fluff initially about a number of people, very smart climate scientists who had developed great models, produced fantastic analysis and diagrams, but it didn't do a lot. So it was fluff. Nobody wanted to buy it, even internally. Looked fantastic and it was great to show it for board meetings or for whatever sustainability images until we realized that actually when we would put this data to use and would go, and this is a real life example, and I can quote it because this is actually in the annual report of Zurich, when we realized that we can use this data and modeling to go to a company like Audi and say, listen, you insure yourself with us against flooding of the River Rhine, which is close to your factory.
You don't want that to happen because it's financial damage, but also stops the purchase of your cars. But actually, with our data, our models, which used to be fluff, we can actually put it into stuff because Audi, if you listen to us, doesn't let us just do the insuring, but also help advise you on how you actually can prevent some of this flooding happening, how you can actually help us give you insights in the probability that this flooding is going to happen, then suddenly becomes stuff because suddenly it can't be like IT, like like like like Audi wanted to pay for it.
So for me, it's not it's not only about about the content, it's clever stuff, but also how you can use it, if that makes sense. Now, Ed, it's, I mean, yeah, let me just hold fire here because I would like to give another example. But this for me is so incredibly strong. Then of course it gets a virtuous circle because in this case, Zurich, but I think these two for other carriers as well, realize HDDM has a lot of value in propping up this small team.
So Zurich invested in developing his team into a proper team working globally. And now this has become one of Zurich's fastest growing services, which actually is not even insurance at all anymore, but it is about helping clients managing risk. And it's very there are dozens and dozens of big companies, multinationals across Europe, but also in The US who've actually bought these services because they realize this is where the risk management philosophy of insurers and knowledge combined with technology actually offers stuff which they are happy to pay for, which they can use.
And the other interesting part is because this stuff, certainly, is not only anymore about risk management, it's about the strategic business of what's happening. I mean, Audi CEO is definitely interested when risk mitigation can help, can prevent stopping the production of cars, which is a completely different thing than covering the financial risk if a flood happens in a factory. Yeah, absolutely.
James BenhamIt is completely different than production risk. But you're right. I mean, there's some, what I'm seeing, and I do a lot of work in workers' compensation insurance, is a lot of discussion around AI turning into a small number, a few very practical tools help identify what treatment should be performed on that particular insured. Hey, this worker needs nurse case management. This worker needs intervention. Or this worker, you gotta look at the pharmacy on this because we have a risk of having some opioid addictions. I mean, there's some really interesting things that there's no, the initial discussions around AI that were kind of the fluff was, Hey, we're gonna auto adjudicate everything.
We're gonna do straight through processing. We're gonna automatically close out all claims and we're not gonna, you know, we're gonna need dramatically fewer claims adjusters. Of course, one of big companies preaching that was lemonade. And, you know, they preached that they had a super small claims team. And then you look at their loss ratio and you go, well, are you sure about that still? You know, when you, yeah, you know, when you have, when you have an underwriting loss, I mean, and so I think that what we're identifying is, Hey, there's some really good applications for technology that if you solve a very specific problem with a very specific tool that you can solve a major burning point in the pocketbooks of profit and loss statements.
So yeah,
Rob GalbraithI'm with that. Rob, what do you got? Yeah. Hanu, I I know I I'm really kinda fascinated on your thoughts and and learnings from your experience. I understand you're gonna be a a keynote at the upcoming MENA Intritech Summit in Doha, talking about this concept of building insurance companies Yeah. From within. So this concept of of intrapreneurship was introduced to me when I was leading innovation team at a a carrier several years ago and and kinda got me excited, but there's also limitations. Particularly, I mean, there's there's resources that you have certainly that startups, you know, would would love to have and and don't have, but there's also limitations and and to me, the first and foremost is actually the mindset of that traditional firm.
Completely. Completely. Would just love, you know, kinda I I hear it come through in some of the examples that you've given, but maybe you can share a little bit just about, you know, what are some of the highlights that are gonna come from your talk or or what are some of those maybe big lessons learned that you have from that entrepreneurship?
Hanno MijerAnd then how does it differ from some of the startups that you're advising today? Big lessons is is is maybe a bit overdoing it. So I think it it is actually the result of a lot of incremental things you do. But but the I wanna refer to what you said because it really does start with a mindset, but that but that's linked to having a very clear understanding what you're trying to achieve. I spoke a little bit about about the last business I ran, but maybe about another unit completely different, which was Zurich's employee benefit business.
This is some years ago. When I was asked to consolidate a couple of small businesses Zurich had, we have less than two fifty million globally, and that's really all units run by actuaries, more or less, and to turn it to a to a global business, we first start to understand really what are we actually selling and who are we selling to? Because, oh, no. We're selling pension arrangements and we're selling them to to to to companies. No. No. No. No. I said, who are we selling to?
Oh, we are selling to to the risk manager. No, we're not selling to the risk manager. We should be selling pensions, selling employee benefits. Who's actually buying this? And it turned out that all that, you know, we were selling to the big multinationals. We were selling to people, but actually we were selling not to the risk manager. We were selling to an HR manager or a pension actuary at other side. So I'll spare you all the details, but then we worked out a proposition around that.
Then the second one was, okay. This is great. But actually, how are we going to get their attention? And, you know, I'm not sure it translates really well into English. But in Dutch, we have a translation which says, you you know, and don't get me wrong here, but this translation the sentence in German expression in Dutch is you catch thieves with thieves. So if we want to sell, you know, a product to the pension actuaries or the HR people at our clients, we have to make sure that we have thieves, pension actuaries, HR people on our behalf who can do that.
So that was then, of course, you build the infrastructure around it, but then you have, you know, I think you guys will both agree, government industry, that actuaries usually do not make for the best salespeople in the world. Right? They're very good in lots of things, but they are not salespeople.
James BenhamIt's almost like it's almost like they have too much in their head to to to to have that. Yeah. They're
Hanno Mijerbrilliant But
James Benhamsometimes ignorance is bliss. Sometimes you can know too much. And I think that might be the challenge.
Hanno MijerYes. I think about other things, and I am an actuaries, know, so I concur. So what we did then was actually change the attitude and the mindset, and we also gave them the tools, the skills to all those actuaries in Zurich that actually it is not only fun to develop a new venture product, it's even more fun and exciting if you can go to somebody who's like minded at the client, explain what we have, and then have them buy it. And lo and behold, within two years, the best selling salespeople of Zurich globally across every line of business were those actuaries who were selling pension funds.
Can you believe it? So that's a very important lesson about mindset, but it also channeling that mindset into the right direction. The second thing is, and going back to James, you just said some kind of blissful ignorance, and I like that. But I sometimes call it some naive optimism. Yeah? And that's probably I have that in spades. There are lot of things I don't know, I'm an incredible optimist and a bit naive. The good thing is, therefore, that you almost forget are not aware of the limitations which are normally applicable in the insurance company.
So you start doing things. And obviously, if you do it in a very, how do you say it, risk free environment, which insurance companies have to be, I get it, you need to really, really put an incredible amount of effort into stakeholder management. Right? It's really how do you get the CEO of the company along? Well, my case, was easy. There was a CEO who was my main sponsor. So that did help, of course, a little bit. But then you guys and both were for global we've been with global insurance companies.
Global insurance companies often aren't global at all. They are global in the sense that they have branches in 50 countries, but actually they all work independent as local entities with the local CEO, with local agendas, local conversations, local targets. So when you build a global business, how do you make sure that you align the interests of that global you with the local people? And it's not as easy that the global CEO say, oh, we have to do it like this. It doesn't work that way. You have to put a lot of effort, continuous effort in stakeholder management and therefore communication.
And that's the third lesson, if you want. We all everybody will say, oh, communication is key. Communication is important. But when you build a business like that, and I think it's the same when you run an Instech, it is you're completely twenty four seven, day and night, you are broadcasting this message. And the message is basically the same, but the way you convey it is different. It's different if you talk to a local CEO. It's if you talk to the group CEO. It's different if talk to a regulator.
It's different if you talk to this actuary who you want to turn into a salesperson, but relentlessly giving the message. And I think another one is also belief. Why I mean, in sports you find sometimes you see athletes coming from nowhere and become a superstar, but it all starts with having belief in themselves and then this discipline to execute, which comes down maybe to I mean, I can make 10 more points, but I realize we are limited for time there, is a realization that it's not rocket science.
It really isn't. I don't believe for a second it's about tackling the strongest or having the deepest pockets or having the wide institution. It all helps. It really is about having the right mindset, the belief, but also accepting that these things, you know, and that's of course where you have to be a little bit lucky. These things are little sprints. There are a lot of sprints, but in the end, it's a marathon. It's about persistency. And then, of course and then I come back again to how important the buy in from the CEO or senior management is because if you don't have it, it's never going to happen.
And I think that all these lessons, and you guys, you know, you've probably more experienced than I have with Ian on the Intritech side, they get all translatable to Intratech. I find out, you know, I work with a company which is maybe moving in the same space as your company, James. It's a Swiss company called Jarola and they are digitizing the claims process. And it's a bunch of guys, extremely experienced claims people, really know what they are doing and have built these fantastic platforms which really bring down claims costs, increase clients' happiness, etcetera, etcetera.
But they also realized that they don't really understand how to push all these soft buttons in an insurance company. So they need a bridge, right? They need advisors. They need somewhere to close this gap between the intertech language, attitudes, technology, and insurance companies. The beautiful thing is that they have a company interest, but as you guys have seen so many times, now an insurance company collaborates with an insured taker, perhaps a partner buys them. Everybody's happy. It looks fantastic, the business plan. The opportunity ends this, and so many fail.
And of course, there are lots of reasons why things can fail. I would argue, a lot of it, because on both sides of the bridge, don't realize that they have to actually work hard to close this bridge, try to speak the same language, and then take some time to make it happen. So that's Yeah,
James Benhamabsolutely. We've had, as we've built a completely new claims platform focused on WorkComp with Terra, our product, we've had to enlist the help of some very senior claims administrators, adjudicators, claims admins, supervisors, license adjusters, and then spend a lot of time in the client office. It is definitely long ball. It is definitely a slow burn. We roll code out, then we go and watch it being used in the office. Then we go meet with the team two months later. Then we make three minor changes and then watch it.
It is, if you're going to do this right, if you're going to really do it right, it is slow burn. I mean, like we, the biggest things we're releasing in our claims platform, the most important ones to our users are not AI functionality. Although we do have all kinds of really cool things in development, The really important stuff is really simple things like EOB attachments to payments so that when I run the report, it attaches everything properly and they can run because their clients are demanding reports and reports and reports and reports and reports.
And so if you're really going to do your job as an insure tech, you have to admit that sometimes Occam's razor, the most obvious solution is the correct one that you, that you just need to really look for, for the obvious stuff, deliver value and be okay. That it's going to be a slow roll.
Hanno MijerKnow, starting
James Benhama business to selling it in five years is probably not realistic when you're in an industry that values stability and in a slow pace of change. They don't go bankrupt because it, you know, it's kind of like an accounting, you know, creative accountants go to jail and insurance companies that move fast and break things generally go out of business. Now you can be completely revolutionary, but it's almost you can be revolutionary and not move at lightning speed. Do have to move. You do have to have a good pace of progress, but your timelines need to be realistic you're dealing with an insurance industry that is A, heavily regulated and B, you have some deep systemic things you have to deal with, like you have to drive underwriting profits every year.
So, balance and all things. That's our time for the show. It was really good talking with you, Hannah. I appreciate you joining us from Switzerland today and enjoy the conference that's coming up. Absolutely. The InsurTech Mina conference. Was going to try and go. And then I had a very important kid commitment that I needed to stay in Texas for. And so that definitely takes precedence and priority. Of course, of course, of course. And so I, unfortunately, I will not be joining you at InsurTech Mina, but I look forward to hearing how it goes and certainly look forward to staying in touch with you and thank you for joining us today and sharing your thoughts with the InsurTech Geek podcast.
Hanno MijerWell, thanks James. Thanks. Real, pretty enjoyable.
James BenhamAnd Rob, as always, thank you for being the world's best cohost and, hope you have a drier, maybe less humid weekends, Antonio. Hey, my hair stays the same regardless. So Yeah. Yes. It does. You have the high speed low drag haircut. And for those of you on listener land who are going to rims, hit me up. I will be there at exhibiting. A booth is called Terra, t e r r a. I'll be there exhibiting. I'll be hanging out in the evenings at the social events.
So hit me up if you're going to Rams. Thanks for tuning in today to geek out our interview with Hannah Meyer. My name is James Benham. This has the InsurTech Geek podcast. See you next time. The InsurTech Geek podcast is all about technology that's transforming and disrupting the insurance world. I've been your host, James Benham. That's jamesbenham.com with co host Rob Galbraith at endofinsurance.com. We're taking you on a journey through insurance tech. So enjoy the ride and geek out.