 YouTube
 Spotify
 Amazon
 iHeart
 Apple
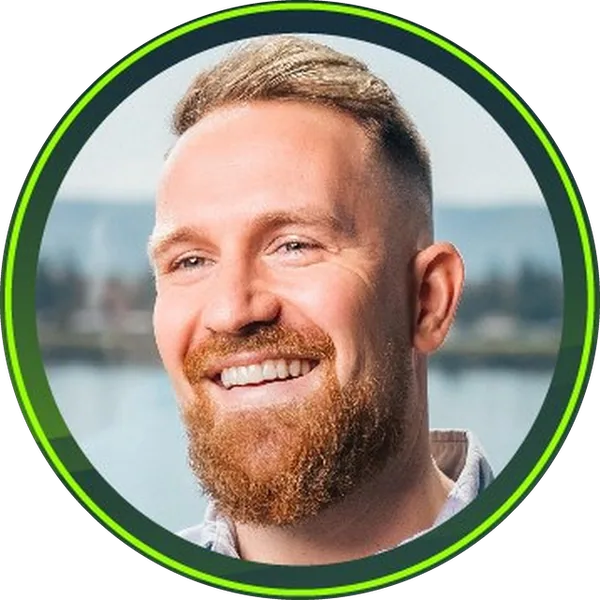
Rudi Pino
Rudi Pino from LUNA Insurance shares his expertise and insights on disrupting the broken status quo. Learn tips and tricks on leveraging tech to provide unparalleled customer experiences and redefining industry standards that are changing the face of insurance.
Throughout his life, Rudio Pino's father and grandfather were involved in insurance. Inspired by them, he began his own journey, holding positions at ASKE Insurance Advisors and GEICO as a Contributor.
After several industry experiences, Pino aimed to create an independent brokerage to contribute and add value to the industry. This led him to found LUNA. At the same time he created Kingdom Capital, which he describes as a passion project for philanthropy, where they work on flipping houses and using the collected money to help the anti-sex-trafficking space.
The full episode
Press play for the whole conversation.
Building a Scalable Model for Insurance
LUNA does not stop at being just an app. Pino highlights that they have a franchise model as they scale their company. To support this, they have a full-stack team of developers that keep building and improving the app and it's surrounding ecosystem.
As of right now, LUNA offers personal lines brokerage, with plans to add to commercial auto lines and test out telematics.
Pino emphasizes their commitment to making processes more convenient for customers, reinforcing the concept that LUNA should replace the time spent on emails, phone calls and walk-in offices.
The Secret Sauce
Pino shared that they just launched their MVP and he is full of hope and expectation that they will deliver on their guarantee that people will never need another insurance agent again.
In that regard, Pino highlighted that even though they don't want to reveal their "secret sauce" for lead acquisition, he did state that they "don't compete in keyword bidding" because there's no way that a "small startup" can compete with insurance giants.
They are betting all their chips to SEO, focusing on backlining, driving value and curiosity, and building quality content. Lastly, he highlights the importance of creating a healthy company culture and building a company that people trust.
Stay tuned for more insights into the world of insurtech with The InsurTech Geek Podcast. Enjoy the ride and Geek out!
From the conversation
LUNA is a technology-based insurance brokerage. Pino shares that their goal is to "replace the typical insurance model" with an app for clients and a backend agency management system (AMS) built out with a Content Management System (CMS) and other tools for the agents.
The LUNA process is fun and experiential. Once the user downloads the app, they submit their information and become a lead. Immediately, the client receives competitive quotes from all the top companies and carriers. From here, the client selects the best price, and an agent guides them through the process.
LUNA guarantees that you'll never need another insurance agent or app again. The policies are displayed live in the LUNA app, which acts as a centralized storage place. It provides one place for everything, you can receive 24/7 service from an agent, request a vehicle change, and add a driver. It's a full line insurance brokerage in an app.
Pino believes that "LUNA allows us to do what Uber and Lyft did for the taxi industry for insurance". This means agents don't need to show $200,000 in the bank with a big-name company, build a team, and be stuck at their desks. Instead, they can use the LUNA platform to work the leads that come through, communicate with agents, and build their own book of business.
The full transcript
Transcribed automatically from the episode audio, so some names and terms may be misheard.
James BenhamOn this episode of the InsurTech Geek podcast, we're talking about disrupting the broken status quo with Rudi Pino from Luna Insurance. The InsurTech Geek podcast is all about technology that's is transforming and disrupting the insurance world. We'll be interviewing guests and doing deep dives into specific tech we see changing the industry. We're taking you on a journey through insurance tech, so enjoy the ride and geek out. This episode of the InsurTech Geek podcast is brought to you by Terra. Learn more about our cloud native risk management information system at terra.insure.
And we are back with another great episode of the InsurTech Geek podcast. Again, I'm your host, James Benham, hanging out here in Texas. It's a hot, swelter y, low tax entrepreneurial friendly haven of Texas. That's right. And with me from a very different place, better weather. I don't know. We're not going to comment on the tax policies, but definitely better weather from Portlandia, from Oregon. Wobegon, Oregon. Rudi Pino, what's going on, Rudy?
Rudi PinoOh, you know James. I'm just I'm enjoying the intro. I just hot, sweltery Texas. You know? I don't know that the weather's better. It's very different. It's it can be freezing cold and wet, which I despise, but our summers are incredible. I think we win we beat Texas on the summer game.
James BenhamOh, for sure. 100% you do. Absolutely. Everybody beats Texas on summer game. But, I mean, we have nine great months a year, like, really great year. You know? And you can come around to fall, and it's barbecue, brisket, football. Oh. Yeah. Starting about September, you know? You know, it's, it's pretty, pretty, pretty freaking amazing. So, you know, you you everything in life's a trade off. If you live in San Diego and have 72 degrees and sunny every day, you have to deal with a whole lot of other stuff out there to to, to to deal with that.
So, you know, there's there's a nice trade off.
Rudi PinoI I do I do enjoy the people in Texas. I like the culture. I like the community. I actually got some good friends that live down there.
James BenhamSo, I'm with you, man. You're my people, James. Rudy, check talked a little bit. Rudy, check this out. Yeah. I want you to check This this is this is La Barbecue from Austin. This is I want you to the the bark the the bark on this brisket here. I mean, that's just that's just some impressive barking. What the some good burnt ends. I'm a burnt ends guy.
Rudi PinoThat's my favorite.
James BenhamCan Rudy, you like if you if you like burn ins, I'm your best I'm your best friend, brother. Come on. You're my burn in, buddy.
Rudi PinoI am. Oh my god. Burn ins. Now I love it, dude. I love it. It's a yeah. I I I'll find you burn ins that don't taste like jerky, you know, like they're good burn ins. So I ain't gonna be mad at them. I like that. I won't be mad at jerky. I won't be mad at the jerky either.
James BenhamYeah. That's great, man. Well, let's talk about you and then we're gonna talk about Luna. Okay. You know, this show is all about all about insurance, all about technology. It's all about geeking out on this nerdy stuff. You know, I I wound up in insurance by accident, like most people, you did not. But I did, I did. I ended up, on accident. I landed a client, you know, started the software company in my dorm room twenty three years ago, JB knowledge. Twenty years ago, I got a client that was an insurance and I was like, man, they need a lot of help in insurance.
And so I started building software for insurance. So twenty years of building policy and claim software for carriers, TPAs, brokers, PBMs, MGA. Now it's, it's been a, it's been, been a long, long path, long path, but, you know, like hearing about other people's path into insurance and, you know, you had a, an, an interesting route through life. You know, you, you do live in the, Portland slash Vancouver, Washington area. You're, you're from that area. But you actually went to school, at a really interesting place called Michigan tech, which is, I'd say nationally not a well known school, but if you like collegiate ice hockey, it's sure as hell well known.
And, and so you played varsity ice hockey for them, and then and then you ended up going to, to Lawrence University and Oregon State. So what was the idea? Was the idea to be a professional athlete?
Rudi PinoYeah, man. Honestly, that was kind of the dream. I was raised by an insurance agent and a flight attendant. So my dad had an insurance brokerage, you know, great in sales, great with people. My mom, immigrant, educated, just grinded, great woman. They raised me with this philosophy of like, you're gonna figure out a way to pay for higher education one way or the other. So either get a job now at a young age and start working, learn that law of labor, or get really good at sports or something that's gonna pay for it.
You know? Get smart, get educated, you know, get scholarships in some way, shape, or form. So I chose the sports route. I was always athletic. Got pretty good at both ice hockey and golf, and it paid for my education. So that's, that's what took me there. I wanted to be a pro, but I got pretty self aware and realized I'm not gonna make millions doing this. So I don't know if I wanna break my body through my twenties to try and get there. And despite that, still made a go of things, in both both sports.
Got pretty far with golf. Life happened, and so I had to retract from my golf endeavors. But I find myself now in insurance like my dad and grandfather when I swore I would never, I swore I would never, never do insurance. And yet here I am trying to like, you know, I don't know, be the Elon of insurance. We'll see. Well, being the Elon of anything is pretty alright in my book. I'm tell you what. Watching
James BenhamI'm game. I love that guy. Watch watching with watch watching what that guy's doing here in Texas is amazing. Oh, yeah. You know, I I got to I actually flew down to South Padre and went and checked out the the Starship. I, like, walked right up to it. And wow. There's no you ain't seen nothing till you seen that that thing. That's the biggest that's the biggest damn machine. It's just crazy to think it flies. And and I I The Gigafactories
Rudi Pinotoo. I mean, the Gigafactories too. He's got he's got these giant compounds, like these structures that are just sucking energy and and producing energy, And it's just it's insane what it's doing. It's insane what it's doing for electricity, electrical commerce here in The United States. I actually saw some statistics that the amount of electric electricity produced in The US has more than doubled from 2023 to 2024, and it's all because it's all attributed really to Tesla and these gigafactories and Elon. Kinda crazy, man. He's making a world impact, and I love it.
And I think his mind's in the right place despite what many people think. So let's get Yeah. It's now his disrupt the body, right? Exactly.
James BenhamRight? I mean, he definitely emboldens a lot of us to like say, okay, I'm not I'm I'm not even thinking on the universal scale that he is, you know, about building machines that traverse the universe. But but, we can definitely rethink how we do stuff here on earth. And, that's exciting. You, you know, you, you got into insurance through ask insurance advisors in 2014. And then you got into, GEICO and, and, you know, you were, you were there for three years, six months at Geico. It looks like it's called Clackamas.
And then you, and then you got into Kingdom Capital. So explain that, that you, you took a track for for you took, like, a nine year track through insurance. And then Yeah. Tell tell me what happened after that. So it actually started when I was 17.
Rudi PinoI got licensed really young. My dad wanted me to get licensed. My dad had a farmer's agency for twenty plus years, went independent back in 2009. And then I more or less inherited the agency, Pino Insurance Agency, LLC back in twenty thirteen, twenty fourteen. I rebranded and that's ASK, A S K E, Insurance Advisors. Built a brokerage is what I did. Niched in construction contractors, commercial lines. Built out a trucking division, actually. Did some heavy stuff. And always personal lines, though, as well. Got an opportunity with GEICO.
GEICO called me and asked if I wanna open some offices in Seattle. I said, no. Not at this time. But if you guys wanna open some more in Portland, Vancouver, I'm down. They called me a year later, and I ended up opening an office in Clackamas. Built it to be one of the top 10 agencies in the country very quickly. Tried to expand and and thought about some different visionary ideas there. Nothing ever really came to fruition with GEICO. They changed a lot as a company structure, etcetera.
They went from about 300 offices in the country down to 150 really fast. And so I exited GEICO and really went full on and committed to building Luna. And Luna insurance is, you know, built off of this premise of changing this terrible customer experience and also the way that brokers and agents do their job. And so I knew that if I wasn't gonna be a captive agent for GEICO, I was never gonna go captive with anybody else. Like, there's no point. GEICO was great because they funneled you with a ton of leads, you could grow an agency super fast and big.
Otherwise, I was gonna be a broker. So I went back to the brokerage world, built out Luna insurance, still have my independent brokerage, if you will. I bought back into the agency, and we're utilizing that agency as kind of a foundation for Luna, which we'll get into Luna and whatnot, but that's kind of the answer there. In the meantime, regarding Kingdom Capital and Pino Capital and different endeavors, I've always loved to add value. So Pino Capital is by which we've been consulting. I just had a really good strong core team with a controller, an administrator, myself.
And we added value to different companies along the way. I helped a lot of insurance agencies grow and scale and fix what was wrong, build out their teams, hire properly. And Kingdom Capital was really an exercise in philanthropy. It's a philanthropic real estate fund. I wanted to flip houses and do new construction and give all the money away because we have some pretty big vision and a big heart towards, you know, the anti sex trafficking space and and and building out shelters around the country for people who've suffered from that, such that they can actually rehabilitate properly.
So that's a that's a passion project, if you will. I'm not really full time on that anymore, because Luna has become so big and so demanding. And so I'm full time on Luna now, and everything else is more or less tabled, until the next season by which, you know, I'll have capacity and and or hand off to somebody else who can make that happen. So Yeah. So let's talk about Luna. Like, it's it's joinluna.com.
James BenhamIf you Google Luna insurance Yeah. It's, there's a couple of results, but this is joinluna.
Rudi PinoSo tell us tell us what it is. Yeah. So Luna is it's a techno it's a technology based insurance brokerage is what it is. So we replace the typical insurance broker model, mom and pop local agency model with an app for clients and a back end AMS agency management system built out with a rater, CRM, etcetera, for the agents. So, on the cons client side, the consumer side, I mean, you instead of emailing or calling, you you download the app. You provide a little bit information in a fun, experiential way.
You submit that information. It becomes a lead. And then immediately, you receive competitive quotes from all the top companies and carriers. You select the best price. You can work with an agent meantime through this whole process as a guide, twenty four seven chat available with agents in the app, again, to replace emails and phone calls and walking into office. And once you bind your policy, we stick with you well after the sale. So we guarantee you'll never need another insurance agent again or another insurance app.
Your policies live in the Luna app as a storage, place, one place for all things, and you can receive twenty four seven service by requesting to change a vehicle, add a driver, whatever you need. It's a full lines insurance brokerage in an app with agents available on the platform. So the platform that we built, because no one would plug in with their APIs to our app, we built ourselves as well. And that platform really acts as the ability for us to do what Uber and Lyft did for the taxi industry but for insurance.
So agents don't need to show $200 in the bank to open an office with a big name company, you know, and build out this team and have a brick and mortar and be stuck to their desk nine to five. They can actually just get onto the Luna platform and work the leads that come through, communicate with agents, and build book of business themselves. So we do have a franchise model similar to, like, how Goosehead Insurance has grown,
James Benhamyou know, as we scale. So that's what Luna is in a little bit longer form. Did you build your did you build your full agency management system, or did you use something like Epic or AMS three sixty?
Rudi PinoNope. Epic, AMS three sixty, none of those people would really plug in with us nor was it cost effective. We have a full stack dev team because my seed investor is actually a pretty large company, and they have a lot of technology developers. And so part of their investment was, full time access to two devs that are full time Luna and then the rest of the team to help supplement as we build out. So you went after them. I that's a lot to build. And AMS is a lot to build.
I mean, that's a lot. Over two years. It took over two years. You know? And and I I actually consulted my seed investor for a period of time before ever really pitching the idea of Luna, because they wanted to capitalize on a lot of auto insurance leads that they're able to generate. They're a marketing firm. And, long story short, like, you know, they agreed with me that the vision for a digital insurance brokerage is needed. The market wants this, and we've just kind of been proving it ever since, we've gone live, which we've written over 300,000 in premium in less than seven weeks just by going live.
And it's all personal lines except for two commercial auto. We're working on our commercial auto flow right now, and I'm hiring a couple of sales agents on that side to manage commercial auto policies. Venture capital's really interested in that. So, yeah, we did. We invested. We're we're about our burn we're at about 1,300,000 invested to date, and it's taken just over two years to get to this point. Things always take longer than you think they are. Tell you what. This is my
James BenhamNo. Yeah. We built we we built about five products before we built our previous product called SmartBid. JBKnowledge is my you know the service company and then we did software development services the whole time and then built products and we built a content management system and e commerce system, internet product, a full ERP. I I've mean been down the road and really none of them stuck until we built this bidding system called SmartBid. We ended up getting over 1,100 paying enterprise clients and then a quarter million companies using that bidding platform.
Wow. Then, you know, sold that into, yeah, it was amazing. I mean, we had 10,000 construction projects bidding out every week. And the tie to insurance is that we had a pre call system for sub default insurance SDI and builders risk policies
Rudi Pinoand bonds. Yeah, I love builders.
James BenhamYeah, too. Me too. It was a great, great space to be in. And we sold that in 2018 and then started building our own core policy and claim software, which is called Terra. And I can tell you just every single product I've built, you know, all the smart products plus smart compliance plus, you know, every everything cost two or three times as much as you think it will. The revenue takes two or three times longer to on board than you think it will And it's half of what you think it'll be.
And it's, you know, it's, it can be, it can be, it can be pretty exhausting. So you've, you've built this thing. I mean, who, who's, who's the, is the customer of the insured and you're making a commission as their broker of record or, or is the is the is the customer the other broker in this franchise model? Like, do have a direct plus franchise? Like, how how does this work? Yeah. So the the first one,
Rudi Pinothe first option that you mentioned, we're a full lines brokerage, and we're selling policies to consumers and servicing those policies, just making it way more convenient for the customer. There's a bunch of other revenue models to this. We actually have six different revenue models that's not just new business and renewal business. We're testing out some telematics based insurance quoting with the likes of GEICO, Root Insurance, Progressive. Those have not gone live yet. I mean, we just literally launched our MVP, which is minimal viable product for anyone watching.
I'm sure you know what that is, James. So, like we don't even have v one available, although it's still adding a bunch of value, you know, where we are currently. Yeah. I mean, I I could get into the rev models, but, at the end of the day, you gotta figure out how to capitalize on your audience. And so we have claims concierge services that we're gonna build in because, you know, why wouldn't you wanna just have your insurance agent help and handle your entire claim? And in return, you subscribe to the Luna app at $49.99 a year, which replaces, you know, a very modest broker fee, for example, from a standard agency.
And then you've got the subscription base. You you build retention. Like, my goal is to get to, like, nine to one LGTP to CAC ratios, meaning lifetime gross profit. Right? I really wanna get really great retention. Really great retention on preferred book of business, people who value what we offer. And, again, deliver on that guarantee that you'll never need another insurance agent again. That's the idea. The broker model, actually, with the AMS, because we took the time to build the AMS, is actually really cool too.
It could be its own company because it's it's more or less like a SaaS. It would compete with the likes of, like, Better Agency, EZ Lynx, IBQ, all of them. But it plugs directly into an app that allows you to basically open a scratch agency. And it's interesting. We haven't even really gone down that road yet, but we definitely see a franchise model in the future. I want to compete with Goosehead. I know they build based off acquisition, buying books, etcetera, but I think that they're kinda behind the curve in terms of their technology play.
And brick and mortar agencies, I think, are gonna be fewer and far between. Okay. I agree.
James BenhamYou know? And I and I I'm I'm interested in in what you're doing. Obviously, I tried to create an account and get a quote before this interview, and it said Texas wasn't available yet. So Yeah. Yeah. Sad sad sad face that you didn't include God's country in your MVP. But, like,
Rudi Pinowhat what what know what? I'm go go ahead. Go ahead. Sorry. Yeah. No. What what states did you launch in? We launched in Oregon and Washington, Tennessee, Arizona. That's mainly it. Colorado coming on board quickly. Texas actually coming on board quickly because it just turned green. But I'm working on direct carrier appointments, plug ins actually with national carrier relationships. So speaking of Texas, ironically enough, I'm talking to Liberty Mutual, the director of national relationships regarding Liberty and Safeco and directly integrating into our app and AMS so that we can clean up the quoting process and also speed up, automate things.
But, I mean, those carrier relationships at that level are very hard to come by, and you really have to prove yourself. So I've been talking to them and bugging them for years, and now we're finally starting to get some traction because they see that I'm serious and I know what I'm doing and I'm committed to building a book of business in the proper manner with attention to loss ratios, attention to liability limits. Whereas players in this space before me really just kinda wrote an insurance policy for anyone that wanted one, and there was no field underwriting involved.
So,
James Benhamthey also don't provide service. Yeah. They and or or claim stewardship. Right? That's the, that's the other big part too, know, is getting that, getting that stewardship process over claims. Now commissions are getting cut by a lot of these personal lines carriers. They're going out to their big agents and cutting commissions in particular on their high net worth, on, on their high net worth business. Right. So the private client division, you're seeing a lot of brokers that are getting their getting their their rev chopped down a good bit by the market.
Are you seeing this? Are you seeing the same thing on the the general personal lines business with your, you know, your average person you're writing? Are you seeing commissions getting cut down? Not really, actually. I mean, in profitable states, they're they're throwing out a lot of incentives. I mean, we have a direct Allstate
Rudi Pinoappointment as a broker, which is very unique. So we carry both Allstate and National General. Is similar to, like, carrying Liberty and Safeco. Yeah. We're one of the only brokerages in the country that actually has that. So to give you to to use an example, they've actually incentivized us continuing to write, you know, the Robinsons as they call them, the premier book of business because they load they know it's profitable. I think a lot of those luxury clientele, they have so much premium that they're bringing to the table.
They're cutting commissions because even if you cut commissions in half, it's still a large check. And so they feel like the carriers feel like they can justify it. And there's a lot more catastrophic risk on that stuff, especially due to California, you know, because of wildfire and, you know, a $10,000,000 house burns down, and that just kills any of your underwriting for the last however many years. You know? So I can see their reasoning, like Chubb and these larger companies and trying to cut that luxury risk.
But, no, we don't see it as much on the personal end side. If anything, it's the opposite from my experience. But I'm also very focused on bringing to the table profitable book. I know that I have to be conscientious of that with the carriers if I wanna win them over and get API access to their raters. Yeah. You can't just write anything. Right? That's just so talking
James Benhamabout is you you've got two big challenges. First, you've got you've got just insurance challenges, and then you have technology challenges. What have have your the biggest have the have the biggest challenges been on the tech side? Have the biggest challenges been around all the integrations with the major carriers? Yes.
Rudi PinoYes. That's been the biggest hurdle. It's being in technology and working with with with large companies that have a lot of pull, that you really have to just kinda like do whatever they say, and they're not technology companies. They're they're they're pretty far behind, and they're a big moving ship. You know? They've they've got a lot of elements at play, and in their defense, it's it's not easy to just to just change something or provide access to something or give somebody APIs. Like, I I realize why they're so guarded, but that is by far the the most difficult hurdle to overcome
James Benhamfor sure. That makes a lot of sense. Makes a lot of sense. I mean, look. I I've had to integrate with carriers for twenty years now, and it's a very very very very challenging, man. I mean, I remember walking into a major commercial lines carrier and they told me they had 38 systems involved
Rudi Pinoin writing a policy. Sorry to interrupt. I mean, to your point, you know, insurance is also the hard part too, because I've been in insurance and on the ground long enough to know that there there aren't very many great agents out there. There aren't many agencies that know how to actually build profitable book of business while, you know, servicing the customer well and really focusing on longevity. And the carriers, you know, are the ones that eat that at the end of the day. They pay a commission to the agent all day long, but if the agent isn't focused on writing proper business, the carriers are the ones that lose profitability.
They're the ones that pay out all these claims and they're working off very slim margin. So I think the other big hurdle in building an InsurTech is carriers' lack of appetite for that kind of volume. You know, with an InsurTech, I can scale nationally like that. You know, give me direct carrier integration and carrier appointments and help me streamline the quoting process a little bit better, especially for my agents. They go from writing 500 policies, you know, a year, let's say, to 5,000 a year very quickly, very easily.
So I can bring on a ton of volume super fast. And as you know, over the last couple few years, insurance carriers are very averse to growth because most agents don't know how to grow properly. That's my thesis. Well,
James Benhamacquiring leads seems to be the big financial challenge with a lot with everyone who's either either the carriers who are direct to consumer or brokers like you. Yep. You know, the the cost of the the the CAC, right? The cost of customer acquisition. Yep. That seems to be the the the the anchor that sinks a lot of these companies or that really just super weighs on their financials because buying Google ads on everybody looking for auto insurance and home insurance, you're up against monsters like Geico that spend what tens of billions of dollars a year and digital and traditional ad spend.
Yeah. Progressive. My gosh, you look at their ad budgets and it's, you're like, oh my gosh, how can anybody buy any keywords around, around personal lines insurance and get any kind of any kind of impression share on search engines. So what is there a secret sauce you can talk about publicly? Yeah. Like, what what are you are you mainly getting this on online? Are you getting this through the personal relationships of the people that work at your company? I can't I mean yeah. Yeah. No.
Rudi PinoPardon me. It's it's breaking up a little bit, but I'm, I'm getting what you're saying. And, yeah, there there are certain things I really I I can't share yet. We don't wanna give away our secret sauce. And then also, My Seed Investor, it's it's a it's it's a top marketing agency in the country, and we develop a lot. We we generate millions, tens of millions of auto insurance leads. The key, honestly, the key and the question really in generating leads is how to generate a more preferred lead.
Not just a higher intent lead with more likelihood to purchase, but a preferred business lead. And in insurance, we know what that means. Right? We want a better client. And how do we generate those kinds of leads? Yeah, we have a bunch of different ways in which we do it. But I think what fundamentally works is having, one, a disruptive technology that actually adds value. Two, branding it really, really well so it's attractive. It drives curiosity. It's enjoyable to use and work with. And then three, like, genuinely company culture.
Like, good is this company at doing what they do really, really well and building a company that people feel like they can trust and believe and buy into, especially if you're a startup. Because you are. You're competing against huge companies that you're not gonna outspend them for keywords. So we don't even fight that fight. There's there's one answer for you. We do not fight the fight of buying keywords like auto insurance. You know? We get very, very creative and crafty in terms of backlinking, winning the SEO game in other ways outside of keywords, you know, having landing pages, knowing how to market and target a certain demographic, and content.
We know how to build content really well. Like, I have not gone crazy on social media, but you're about to see a lot of what we've been building for the last six months. And it's gonna go off hard and fast. And, yeah. I mean, I'm also focusing myself on being, a thought leader within the space and being a true contributor to the next generation of insurance agents, brokers, investors, just the space in general. So I'm, I'm trying to stay educated. I'm trying to really add value.
I'm trying to be a good salesperson that people can believe in and then therefore
James Benhamdrive traffic to my technology, my brokerage, my company. Nice. And you have a series you started called the Diary of a Lunatic CEO, a little play on the words lunatic. That And that that's all about So so where can people check that series out, and where can they find out more information about Luna insurance?
Rudi PinoSo go to LinkedIn if you wanna follow my my test, my little experiment, diary of a lunatic CEO. Every day, I'm recording myself for thirty seconds at least and just kind of exposing my life as I build this thing. Yeah. And then posting on Instagram a little bit right now, but if you look up joinluna.com or you search join Luna app on Facebook, Instagram, anywhere where you see join luna, you're gonna see a black background with a white logo that says Luna with a little smiley face.
That's us. And we're working on trying to get, all the the the search keywords for Luna itself because there's a couple of people in the space, agencies even, that have the same name. But you'll find us if you search join Luna app or in the App Store, Luna Insurance,
James Benhamor myself, Rudi Pino. That's awesome. Rudy, we are out of time, but I really enjoyed the conversation. Love hearing about what's going on at Luna, your your story. We'll do a follow-up with you, as you, as you go through the space. I I, of course, will will follow your your Diary of a Lunatic CEO. You can check that out of course. You can you can check all of my musings out at jamesbenham.com or on my LinkedIn channel as well. I have a I have a a really cool series we're doing on bootstrapped innovation where I interview a lot of bootstrappers that decide to bootstrap instead of raising money.
That's a little passion of mine as well. So, Rudy, I really appreciate it. Best wishes. Good luck. I'm excited about what you're doing with Luna and really excited about, the outcome. As soon as you open up in Texas, I'll be getting a quote.
Rudi PinoAwesome, man. I love it. I love it. You might be my first Texas client. I might just send you the app right when we go live so you can let me know.
James BenhamSend it to me first so I can I can be your first Texas quote? That that would actually that would actually make me deliriously happy to be your first Texas quote.
Rudi PinoSo We're gonna make it happen. I'm I'm gonna stick to my word on that one, man.
James BenhamOkay. I like it. I like it a lot. I like it a lot. Alright. Well, thanks a bunch. I appreciate it. Thank you to all our listeners for tuning in today to geek out our interview with Rudi Pino from Luna Insurance. See you on the next InsurTech Geek podcast. The InsurTech Geek podcast is all about technology that's transforming and disrupting the insurance world. I've been your host, James Benham. That's jamesbenham.com with cohost Rob Galbraith at endofinsurance.com. We're taking you on a journey through insurance tech. So enjoy the ride and geek out.