 YouTube
 Spotify
 Amazon
 iHeart
 Apple
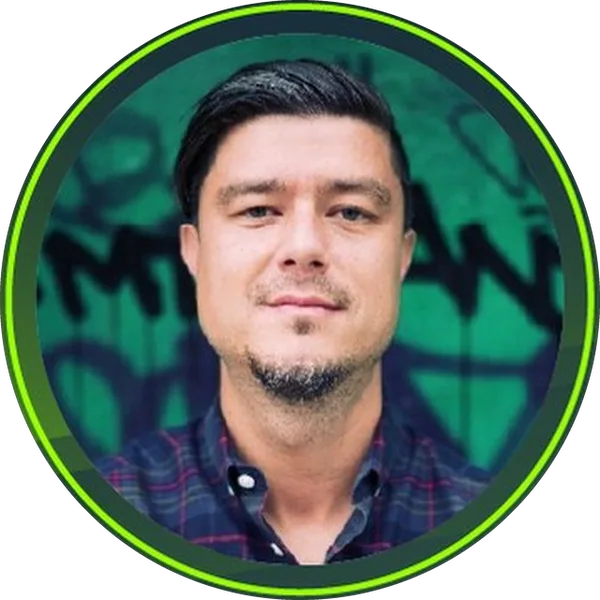
Yann Barbarroux
Yann Barbarroux from Otonomi shares his insights on bridging supply chain gaps with cargo delay insurance. Learn how innovative solutions can mitigate supply chain risks and provide peace of mind during global disruptions.
In the latest episode of the InsurTech Geek Podcast, hosts James Benham and Rob Galbraith delve into the world of cargo delay insurance with special guest Yann Barbarroux. As supply chains grow increasingly complex and global trade faces numerous disruptions, innovative insurance solutions are essential for mitigating risks and ensuring smooth operations.
Yann Barbarroux, a pioneer in parametric insurance, sheds light on how his company is addressing the long-standing exclusion of delay coverage in traditional marine and cargo policies. Through parametric insurance, claims are triggered automatically based on predefined parameters, such as transit times, without the need for a lengthy adjudication process. This approach not only ensures quick payouts but also brings much-needed predictability to the industry.
The full episode
Press play for the whole conversation.
Innovative Insurance Solutions
Simplifying Claims Processing: Parametric insurance eliminates the traditional claims process, providing swift payouts within 48 hours of a triggering event. The use of real-time data and automated systems ensures transparency and efficiency.
Addressing Exclusions in Traditional Policies: Historical exclusions in marine and cargo insurance policies have left gaps in coverage, particularly for delays. Yann's company is bridging this gap by offering a product specifically designed to cover delays, providing a new layer of protection for shippers and freight forwarders.
Leveraging Technology for Real-Time Tracking: Advances in GPS, satellite technology, and IoT sensors enable real-time tracking of cargo, crucial for triggering parametric insurance claims. These technologies also help in dynamic pricing and risk assessment, enhancing the overall efficiency of the insurance process.
Global Impact and Adoption: The demand for cargo delay insurance is growing, driven by the increasing complexity of global supply chains and the rise in geopolitical and climate-related disruptions. Yann highlights the importance of educating the market and establishing strong partnerships with data vendors and logistics providers to ensure the success of this innovative product.
The Potential of Cargo Delay Insurance
The introduction of cargo delay insurance marks a significant advancement in the insurance industry, addressing a critical need for more predictable and efficient risk management solutions. As technology continues to evolve, the potential for further innovation in this space is immense.
Tune in to the full episode to learn more about how Yann Barbarroux and his team are revolutionizing the insurance landscape with parametric solutions.
Stay tuned for more insights from industry leaders on The InsurTech Geek Podcast!
The full transcript
Transcribed automatically from the episode audio, so some names and terms may be misheard.
James BenhamOn this episode of the Insurtech Geek podcast, we're talking about bridging supply chain gaps with cargo delay insurance with Yann Barbarroux from Autonomy. The Insurtech Geek podcast is all about technology that's is transforming and disrupting the insurance world. We'll be interviewing guests and doing deep dives into specific tech we see changing the industry. We're taking you on a journey through insurance tech, so enjoy the ride and geek out. The sponsor of this InsurTech Geek podcast episode is none other than JBKnowledge. JBKnowledge's insurance technology services provides technology solutions for the insurance industry specializing in the property and casualty insurance sector.
Learn more about JBKnowledge at jbknowledge.com.
Rob GalbraithAnd we are back. Rob Galbraith, most interesting man in insurance. How are you doing, buddy? I'm doing well, James. Managed to avoid the, the recent hurricane burrow here in San Antonio. Didn't even get any rain that day. We went out and had a nice round of golf. Well, I should say nice. It was, I got my money's worth a lot of shots. Yeah. Got a 100 on the golf course, not in a good way.
James BenhamAnd a 100 degree temperatures too. It's it's interesting. You know? College Station, we got a good bit of rain and probably about 50 mile an hour winds. And I tell you what, though. Houston Houston got smacked out a little bit. I I I just got back from New York. I was up there on you know, when the hurricane hit, then I flew back to Houston. And I got out of the airport, and man, it was mass chaos. You know, the all the power's out everywhere. There's generators running pretty much everything around the Houston Airport, including the hotel there, the airport where my car was parked.
And the all the gas stations are shut down because they don't have power and, you know, multi hour lines to get gas. And I mean, it was it was it's it's banana land. It's it's crazy. It's a it's a crazy crazy deal. So I am I am I'm currently in Dallas at the Insurance Council of Texas PNC Conference here, and so I'm enjoying being in a city completely unaffected by the hurricane. And so in in enjoying this, and I'm excited about our conversation. Jan, how's it going from from New York City?
Yann BarbarrouxYeah. Thanks a lot for having me again. You know, I was here, I think, three years ago, as you mentioned. Glad to come back. There's been a lot happening, so glad we can we can get an update on our progress and and glad that you get running, like, a very terrific podcast episodes for the industry. Yeah. I'm I'm based in New York, back in New York the past two weeks, but I was on the road for two months. We can talk about it later. A lot of the cities in Asia and Latin America are now now back in US.
James BenhamAwesome. Yeah. For our listeners reference, we interviewed Jan back on 11/04/2021. That's episode number 67, and they'll be posted in the show notes. So we're not gonna do a personal background with Jan because we already did it. You wanna listen to that, you wanna hear about the background story, go to episode 67. And we in fact, this was at ITC Vegas twenty twenty one. So just a little side note, was at InsurTech Connect, which I'm actually really excited to say I'll be speaking at. Rob, I didn't I don't think I told you yet.
But interestingly, InsurTech Connect, ITC, and National Comp are running in the same hotel at the same time. Oh, wow. Okay.
Yann BarbarrouxThat's gonna be Yeah.
James BenhamTwo and I'm speaking at both of them. So you have two major insurance conferences in the same hotel in Las Vegas at the same time in the same convention center and different floors. So I will be walking back and forth between the two conferences, speaking and podcasting and doing some other fun things. So it it interesting. You know, as you know, we build work comp software. Our for for the listeners who don't know, I have two companies, JV Knowles that does, you know, custom software development for insurance companies.
We do, you you know, manage maintenance and that kind of stuff. And then Terra, which is a work comp claims and policy software. So National Comp's a big conference for for us, but so is InsurTech Connect. So I'll be excited to be at both of those. So let's get back to January. Jan, it's been almost almost three years since we we spoke to you. It's been, you know, two two and some change, and we're we're glad to to certainly have you back on and to talk about what's been going on with Parametric Cargo Insurance.
Just a a quick one sentence reminder about what the Hell Pet parametric cargo delay insurance is.
Yann BarbarrouxYeah. So parametric, you know, insurance is a little bit of, like, esoteric, you know, scary word. But the long story short is, it is not an identity based insurance. Instead, parametric gives you ability to have predictability of the amount received, the claim limit. There's no adjudication involved. The second point is there's no claims process and there's no proof of loss needed. Because if the event and the trigger happen, you get the full limit and you get paid fast. Right? Because it's automatic, it's data driven. So we pay out as quickly as forty eight hours in certain cases.
So that changes dramatically from multi months type of process you have to go through. Now in our case, the parametric the parameter that we're actually looking at is the transit time. Right? So the cargo transportation transit time. If we observe a delay beyond a certain threshold, then we pay out. No questions asked. Right? So that's the simplicity of our product.
James BenhamSo in essence, it's gambling. Right? I'm betting on an event happening, and I'm getting paid out if it happens.
Yann BarbarrouxNot at all. It's not that we're
James BenhamOkay. Well, let's on
Yann Barbarrouxpublic episode, I'm I'm gonna be in trouble. Okay.
James BenhamOkay. So so do I have to actually have cargo insurance to cargo shipping to buy the parametric insurance on it? Yeah. That's correct. It is not a speculative it's not a speculative product.
Yann BarbarrouxRight? Yeah. It does have some component of, you know, trying to maybe predict, you know, certain events like the hurricane in Texas, which would be disrupting, you know, both maritime and air. Like no doubt about it. But the central point of our product is the shipper or the freight forwarder involved into buying this delay insurance product from us has to have the insurable interest.
James BenhamIf they don't have insurable interest, we we don't offer the product. Right? Yeah. And that's the that's the thing, of course, why I was being facetious in in my in my comment because certainly that's that's what we'll see immediately when they hear about Parametric Insurance. Like, oh, it's gambling. I'm like, no. You you have to have this magic phrase, insurable interest. You actually have to have a stake in it. Otherwise, it is gambling, and, you you know, you actually pay income tax on it if you if you don't have an insurable interest, you know, the loss.
Mean, there's a a whole bunch of things that come into play. But because you have an insurable interest, you're receiving a payout on a on a on a loss event. It's just a a lot quicker, a lot smoother adjudication process, because you you have the ability on your own to independently verify that an event happened and then make a payment based on that event, being happened with the with the obvious connection that there's a a loss on a connected insurable interest. And so I can't go buy your cargo loss insurance if I don't actually have cargo shipping because I don't have an insurable interest.
So I would have to go ship something and then buy your insurance on it. And so that's the that's the that's the big difference. And I just wanted to point that out for all our listeners when you think about parametric insurance, the big difference between parametric insurance and just an online bookie that lets you bet on anything. Because there's there are some blockchain websites right now, Jan, and I've been I've been really, like, following this and and kind I kind of dove down the block the the the, you know, the crypto and blockchain rabbit hole on this that, you know, allow you to bet on any kind of event that's verifiable by third parties using using Bitcoin.
But because there's no insurable interest, it's it's just online. It's just straight up gambling. Right? They have to run it. They have to run it offshore. So it's very, very different, very, very different, premise, similar technology because you can verify that these events occur. So in in the almost three years since we talked last, how how has this business model evolved? How have things changed?
Yann BarbarrouxYeah. So I kinda wanted to kinda recap why we're doing what we're doing. Right? It's not so much that we facilitate a process and make it smoother. Right? The foundational principle is actually we're bridging an exclusion. Right? A protection gap in the industry, which is cargo delay as apparel, is being excluded from marine and cargo insurance policies. And that's actually both a legacy reason and second, a technology reason. Right? So the first reason is the first maritime marine insurance policy was written in at the Lloyd's of London, which was a coffee shop in the sixteen hundreds.
And they were protecting the commonwealth export of spices, garment, and whatnot. And, you know, on the back of their coffee shop, they're saying like, okay, if the vessel sinks, you've got some damage to your goods, we can write this piece of paper that here's your maritime insurance policy. So that's where the slip was born at Boyd's, really. And since then, that's the irony of the thing is the language barely changed. So delay was excluded from the 1,600 and is still excluded in your traditional policies. So we're kind of bringing and grasping this exclusion and productizing it to make it now a value add to the customer and a new value, a new protection that they can purchase in the market.
And for that matter, we first to market. We're the only one offering the lane insurance in that format. The second reason was technology driven. Up until, I want to say seven or ten years ago, the democratizing of access to reliable and secure API clouds, sensors, GPS satellite technology for maritime tracking, aircraft tracking was not up to par. And the advance of those technologies are now enabling for real time tracking at affordable cost. And so the intersection of those two reasons is why the time is right.
So why are we actually doing what we're doing right now. Yeah. So and then it's it's been actually very eye opening the past couple years, like, being on the road, talking to shippers, cargo owners, freight forwarders, logistics, insurance brokers around the globe of the amount of losses, the amount of unhedged and unmitigated exporters that they keep hearing from customers. Right? So the the main root cause of those losses are essentially a number of things around global macros, for instance. So you can think about geopolitics being one of the most disrupting effect.
Right? So US China trade, Ukraine, the Swiss Canal, Panama Canal, soon to be Taiwan being, you know, geopolitics problem. So everything is kind of creating a lot of those problems between countries. The second one is where you started the episode. Right? So hurricane in Texas one more time. Right? We have like one of those climate disruption. And that's disrupting a lot of the global transportation by air, by maritime, over the roads, you name it. And there's a flurry of idiosyncratic risk that you can observe, collision between vessels, cyber risk, the Baltimore event a few months ago.
There's a long list of issues that keep disrupting this market. While it's actually less and less easy to transport goods and commodities, the market is growing at a parabolic rate. There's an exponential growth of demand, namely 45x growth the past few decades in global trade. Now nearly 25,000,000,000,000 of commodities being moved every year. It's a huge market and the transportation
James Benhamlot of insured it's a lot of insured value. It's a lot of insured value. Yeah.
Yann BarbarrouxSo that's what we're facing right now.
James BenhamWow. You know, just a little little minor detail. You know, the first the because I'm a history nut. The the first maritime insurance was was actually four thousand years ago. The Babylonians wrote Bottomry contracts, and and and people propagate this Lloyd's of London being first, but it was actually the Genoans in 1347 that that, that had, maritime insurance contracts. In that crazy, the Italians actually were first to the table. They had a little challenge because the church didn't let you charge interest at the time. So they had a little they had a little they had a little challenge with some of those contracts, but, the the word policy first showed up, in the in the, fourteen hundreds, if I remember correctly, about two hundred years before Lloyd's opened its doors.
So Lloyd's obviously is the origin of the modern marketplace, but I do wanna give a little bit of credit to the Genoans, the Italians, and the Babylonians for originating the concept. Just like when you're talking about flight because I'm a pilot, you gotta give a little credit to the Brazilians because they did a whole lot of flying around the same time the Wright brothers did, and the Brazilians claimed they were first in flight. There's always a few edges to the story. So, look, shipping things around the planet because obviously maritime insurance has been around for four thousand years, has always been really important, and certainly it made or broke the backs of the economies of many countries in the the in Europe and The Middle East and North Africa for for a really long time.
So this has been a major issue for people for a very long time is is ensuring this. Now we have the ability to track literally everything. I mean, I feel like I feel like there's very few things that we can't track now and identify in real time. Like, one of my friends was the founder of, you know, marinetraffic.com, and really, that was a really interesting business that he ended up selling. But, I mean, they they were able to detect when, you know, North Korean ships were off boarding their goods off the coast of Japan.
I mean, they they could tell they were stopping and docking next to another ship and off boarding. So you can tell all kinds of activity you can track. We can track all kinds of weather activity. Now you can just connect all of it. Where do you think all this is headed? I mean, is is there really a deficiency in maritime insurance, that that warrants a whole lot of innovation. I always like to ask like, where's the real problem now that's not being solved by the traditional maritime insurance industry?
Yann BarbarrouxYeah. It's a very good point about the, Jamil, And I'm going back to your first point. And surprisingly, lot of the maritime insurance brokers are actually Italian. We're dealing with a few of them. And it is true that they were innovator in their own time. But, you know, to your point about maritime traffic, by the way, I'm still waiting for the the intro. I would love to talk to them. Just kidding. But I think it could be interesting to if we can partner with them. The the current gap in the industry that we're facing is essentially what I was trying to explain.
This in exponential growth of demands, right? And you can think about Tmall, Sheen, those e commerce products, which are both maritime and air. And the logistics being essentially operating as if it was 1994. So there's a big gap. There's a few decades gap in terms of the demand and the supply. So the operations capability from the existing incumbents. Right? And embracing the technology and adoption is what's being currently a challenge. It it's being adopted, and that's transforming. But it doesn't take a few months. Right? We we talk about the next decade to to bridge that gap, and that may that might be ambitious.
And one of the resulting effects from this gap, I was toying some numbers five minutes ago, one that's very interesting to actually focus on is nearly 90% of cargo to containers at sea and by air are actually uninsured or underinsured right now. Right? Huge gap in terms of the even the coverage of the existing markets. Right? And when you're saying real time tracking, IoT sensors, trying to get the real refined data and granularity of data, I think we have a full wealth of reliable data. It's not being utilized by insurance company right now.
And I think we're one of the solutions that's trying to bridge the gap and connect the dots effectively. There's other players that are doing a great job as well. But we're going the route of full data enablement, quantitative algorithmic underwriting, and real time tracking and triggering events in a very rapid and fast and transparent So in our case, parametric delay is actually a very obvious product. It's a low hanging fruit, quote unquote. We're already working on parametric damage type of products where we can leverage computer vision and other sensors in order to trigger payment based on perishable damages and destruction, or vaccines, life science.
There's the flurry of other parametrics that can be developed in cargo and global transportation. So very excited about the next few years. Yeah.
James BenhamHey. You should be. That's incredible. And, you know, when you're talking about, you know, ease of underwriting, ease of claims handling, ease of payment, I mean, dramatically facilitating these transactions and certainly, ensuring the under or uninsured is a a major social good as well as, yeah. Well, hell, I just drove through a hurricane riddled area with a with a large number of people who are under or uninsured, and it was a a good reminder of, how devastating it is when people can't or don't get insurance.
It's a major problem. It's a it's a major, major, major issue for society. You know? Interesting. They all always turn to their governments to bail them out when they when they don't have enough insurance, and that's a that's a that's a major issue. Rob, what you got?
Rob GalbraithSo, Jan, I'm hoping, at a very high level because I I know there's a ton of detail and a ton of work that kinda goes on behind the scenes to allow you guys to do what you do. But for our audience, you know, I'm sure, like me, you know, they're trying to wrap their head around this. The the the the need is there. The product market fit is kind of obvious, but I'm just kind of curious, how you do what you do. So maybe you can peel back the curtain just a little bit.
Obviously, your clients, I'm sure, give you information, right, about their shipping routes, whether it's a flight, whether it's a shipment, etcetera. And you've got some track record of, you know, hey, these arrived on time. These have been delayed for these reasons. But, you know, I think about the you mentioned some of the, you know, idiosyncratic reasons like a crash. You mentioned hurricanes, you know, there's an individual event like a hurricane barrel that we're just talking about, but then there's, right, like, what's the ocean temperature this year?
What's the hurricane outlook this year? What's climate change in general gonna be in the next ten years, the next twenty years? Then you've got some of this geopolitical risk. I think about like the Houthi rebels and some of the Red Sea, you know, attacks that we've been hearing about and and that's something that, you know, once that changes, right, the the the risk dynamic, you know, that's gonna stay probably for a few months to possibly a a few years is kind of an elevated risk. So, how does your product work?
First of all, know, is it like based on time? Is it based on, you know, each shipment is its own kind of contract, I guess, so to speak? And then how do you how much information you take in from your client, then how much are you bringing in kind of outside or external information to create some of your modeling to price out the product just to make sure that you're able to underwrite this risk at a profitable level?
Yann BarbarrouxYeah. Now, fascinating question. Thanks a lot. So I want to backtrack a little bit from our last discussion, give you a quick recap. And I think, James, you were asking it upfront. So 2223 on this year, right? So this is we last chatted. So we went through the Lloyd's Lab in '22 and we created relationships with our Lloyd's underwriter. We also met a bunch of reinsurance insurance companies. So we created a lot of our network, not only in US, in Bermuda and offshore. So that was one of the milestones that was achieved back in 'twenty two.
Then going in 'twenty three, we launched our first product, an aviation product, so Air Cargo Delay, which has a good amount of success. It's also a niche market, much smaller than maritime, as you guys can imagine. So we have decent volumes, but then always looking forward to the ocean ocean freight as our home run. And then we eventually rolled out and launched our maritime product this year. Right? So that's been kind of the few milestones I wanted to give the audience a little bit of of the recap and the rundown.
Right? Now while we we went through this process, there was quite a bit of learning experience. Right? It's from both the market, the customers, but also the the partnership. Right? And few of the wins that I'm incredibly satisfied and incredibly, you know, grateful for is we built a partnership relationship along the ways. And one of the most critical ones is the right data vendor and data partners that we're actually working with. And if you look at the news the past couple of days, we actually signed a partnership with Overhaul, which is one of the leading risk management and logistics visibility provider in The US for cargo and logistics.
And that's one of those partner that we essentially getting quality data and also the right network to propagate our product. So we created those partnerships along the way to create this real reliable and secure real time cargo tracking, both in aviation and now in maritime. I think that was one of the key foundation of how the platform can work properly, and that can be completely independent from, let's say, an adjudicator after the fact who tried to justify a loss because of a delay. Right? So we're completely independent and with third party and we're trying to make it very transparent and fast.
So so with that, we we only work with what the freight forwarders and the shippers are actually working with on a day to day basis when they manage shipments and they move assets from a to b, which is either the bill of lading, the container ID in maritime, or the airway bill, which is the air cargo transportation ID. Right? And with that identifier, then we take over and we essentially manage the rest of the policy. Right? We don't need the customers to update anything. Everything's automatic.
Everything is real time. So that that was a lot of this platform build that we worked on the past eighteen, twenty four months. Right? So quite, you know, chunky amount of work and engineering, and, you know, very glad that we we are at the spot that we're at right now. And in terms of your question about underwriting, real time access, external data, so we acquired in excess of 12,000,000 worth of proprietary data in freight, logistics, cargo, and terminal data that we essentially ingested and turned into the black box, the AI machine learning to essentially spit out dynamic pricing for our customers.
Then we always try to essentially gear towards customer value and bring the most affordable pricing we can for the right product. So we just launched a three hour delay by air. Right? And that was on the back of a lot of the perishable exporters out of Latin America and also, like, some life science logistics that are very concerned about vaccine destruction, for instance, or medical specimen spoilage. In that case, we want to essentially fine tune some of the products, but also keeping an eye on the underwriting loss ratio and profitability.
So that's always a game like a balancing act between those two. And in terms of more external factors, so we're starting to consume some of the climate and weather data, whether public or to external sources. But really what we want is being ambitious in the future. Really going for the full gamut of climate risk and running the cross correlation between different factors and bring the most affordable pricing, but also look at loss ratio and performance in the future.
James BenhamCool. Jan, how big do you think this market's going to be for you? Is this is this a billion dollar market?
Yann BarbarrouxHopefully, it's it's 50 of those billion. Yeah. So which bag that I'm sending my investors is 50,000,000,000 market size.
James BenhamThat's an incredible market. Is is distribution because this is a a nontraditional product, are you having to do a lot of client or prospect education to really explain this? Is it difficult to get people to understand? I mean, what's it would seem to me like your your primary challenge now that you've hashed out so many technical details is distribution, just getting this product in people's hands and explaining how much better it was.
Yann BarbarrouxYeah. I think you you nailed it. I think it's it's actually eighty twenty. Right? So 20% difficulty in building platform, 80% is education. It's nice problem to have. Obviously, we're kind of bringing good news to exporters, to, you know, shippers, cargo owners that did now have access to something they've been waiting for for so long. But then, you know, some of it is actually explanation, education, a lot of back and forth conversation, building marketing material for them to explain their customers and whatnot. Some of them is also fine tuning the product itself, as I said.
Right? So we we had a 12 delay by air. We just launched a three hour because now three hour is what our customers are asking. And there's definitely some more, you know, new product feature we'll be launching in the future. But as far as the distribution channels. Right? So our go to market, we work with three types of channel. So the first one has freight forwarders. So logistic PPLs, time critical logistics. So what they do is they they have insurance as one of the service lineup they offer to their customers.
Right? AKA cargo insurance, the traditional cargo. So now we're creating a new product within their toolkit. We're offering them to upsell, to create new value, to reopen conversation, to say, okay, you've been suffering delay risk for so long, now we have that product. It's powered by autonomy, and it's like this, this, and that. Right? So this is one of the channels. The second one is insurance brokers. Right? Obviously, you know, the Marsh, the Aon, the Lockton, the Gallagher, they manage huge portfolio in marine cargo. They have very established relationship with large corporates and 3PLs.
So we're essentially going back to market with them. So there's different type of distribution strategies, but they obviously have great experience that help us getting access to log accounts. And the final one is direct clients. So I was on a road trip, I mean, on the roadshow the past couple of weeks in Latin America, for instance, Chile and Peru. And I talked to salmon exporters out of Chile. They're actually the largest, the second largest exporter of salmon behind Norwegians, which is interesting. I didn't know that.
They they also like the largest export of cherries. Cherries export is actually starting in October and November, and it's actually fitting into the Chinese New Year in the February. So there's a lot of, like, delay risk, and they wanna mitigate those risks. So preparing those conversation and how to structure the program in order to manage their exposures in in the most effective way. So there's many of those situation and conversation, and I'm glad to be first to market, but that comes with a lot of efforts and education of the market themselves.
Yeah.
James BenhamAbsolutely. Rob, wrap us up.
Rob GalbraithYeah. Jan, I'm really fascinated by this, and it's so great just to kinda hear kinda what you were conceptualizing in 2021 to see the actualization of it, and expansion and the product innovation in in 2024. So that's outstanding. Maybe you can just kind of share with us a little bit about some of the regional differences or or challenges. You know, you mentioned Latin America, certainly Asia Pacific, The US, like, you know, are there, you know, I'm sure some problems are common globally, right, like hurricanes, but others are gonna be kind of maybe nuanced to a particular region.
And then finally, like, where do you see further product innovation in this space going?
Yann BarbarrouxYeah, absolutely. Just to give you a sense of our product strategy and quite frankly our go to market strategy, we very much focus on what we call trans specific traits. So Asia to Americas. So both Asia to North America, but also South America and conversely. So Latin America exports to China and so forth. So this Pacific trade is 60% of the global trade. This is the largest chunk. We're not excluding any export to Europe as well. We're part of that you know, conversation, but this is where we find the most interest overall.
Right? Americas to the to Asia Pacific. And the nature of the market is is obviously interesting. There's a lot of different colors and flavors depending on where you distribute. And you guys are actually expert in this space. Right? So if anything, you can give me your 2¢. But what I'm essentially talking about, half of my day is admitted product, non admitted licensing, getting access to a front end company on a direct basis, reinsurance basis, using Lloyd's, using Bermuda, using other underwriters. That conversation is, you know, complex.
It's fascinating. But at the end of the day, I would love to be able to sell my product without having to, like, go to the red tape, like, you know, the day in and day out. Right? So that that's a big consideration. Right? So I'm literally, like, spending a few hours a day talking to reinsurance company, reinsurance brokers, frowning companies, to launch new products in certain regions. But then the other aspect that's also same, same, same different is distribution setup. Some of the distribution or logistics incumbents that's in Latin America are allowing a lot of commission markup and they're more freely trading.
Some markets also more regulated in terms of the commission structure being controlled by brokers. So that's also a consideration that we have to think about you know, when we enter a market. Because we're all about compliance. Right? So we we, you know, I eat compliance for breakfast every day. I spent, you know, over two decades banking and insurance industry. So for me, only doing this thing, it's I'm going to be compliant to the local laws and regulations. So that's creating a lot of complexity, but glad to go through it.
Again, that's the pros and cons on being first to market. And then finally, yeah, so the customers, the market are responding positively. Obviously, they need that product, but it's a different type of response and risk appetite. We don't have the same perception from perishable exporters, whether they are in South America or they are in, say, Indonesia or Malaysia. While at the same time, the product could be very similar, but the way they actually operate and they ship and what kind of ports and carriers they rely on, you know, to transport from a to b is also a different process.
So that creates a lot of, like, feature and and a different, you know, kind of layer of complexity that we have to deal with even the even if the the product is very similar in nature. Right?
James BenhamAwesome. Great conversation. I really enjoyed it. I'm excited to see what's coming in the future. Certainly, I hope it's a $50,000,000,000 market for you. That would be amazing and exciting. And, yeah, you'll have to do a party a party in the ancient ruins of Babylon if you if you if you get to that point. You know? I I expect a big blowout, and then maybe go to London for your next stop. Side side note, do you follow do you follow football soccer? The real the real football that you play with football?
Yann BarbarrouxYeah. I know I know you're coming up with a joke to me because you you just lost yesterday in the semifinals. Yeah.
James BenhamIt was well, it's not a joke. Not a joke. I just was curious since it was in your neck of the woods. It was over there, and and my my my boys from Argentina managed to sleep by and are are headed on to headed on to Miami. Should be an interesting final. So for anybody not watching the America's Cup, it's been a really exciting I went to the Argentina Ecuador game in Houston, and it was a squeaker. Went to penalty kicks. And then the the game against Canada, actually, you know, was it was two nothing, but it was a it was a tight two nothing.
And so it was it was a really exciting match, and I cannot wait. I think the if you're a soccer fan, I, I I think this is a amazing time to be alive in in North America because we're edging up on having the World Cup in North America two years from now. I feel like the America's Cup is just a preview of what what what it's gonna be like to go to different games around the around North America, in Canada, in United States, in Mexico. So, Yan, I'm I'm, excited that you're that the Canadians got to the, to the semis.
Sorry that it didn't work out, but, I'm, real real really, really fired up about about the finals in Miami. And, obviously, I'm personally hopeful Argentina's gonna pull it off because I've got a a a pretty big crew down there, so I'm excited about Argentina. Rob, did you, did you watch any of the games? So I've been focused on the Euros, and, my wife is a pure German. So, unfortunately,
Rob Galbraithyeah, Spain took us out. So kind of in that point where you're like, do we cheer for Spain now so we feel better about going out in the quarters or not? So Yeah. You do.
James BenhamNo. I think that's the universal rule in all sports, Rob, is you you cheer for you cheer for the person to knock you out because it makes you feel better about being knocked out. Could have been second. Exact exactly. Exactly. So exciting time to watch soccer. All the teams are great, especially the ones make it this far. So, anyway and, really enjoyed the conversation and Jan. I'm really hopeful for Autonomy. If people out there wanna find out more information, that's autonomy. That's otonomi. Autonomy.ai. Autonomy.ai is the website.
Correct?
Yann BarbarrouxCorrect. So my email is netyan@autonomy.ai. You can find us on LinkedIn, Twitter, and, you know, glad to grab a Zoom call with whoever is interested in learning more. And yeah. So thanks a lot for having me. You know, I was talking about the euro myself as well. So actually, France lost to Spain, and that was my disappointment. But, you know, I'm glad for Argentina to move to the Copa America spot. Yeah.
James BenhamI Jan, the reason I connected in Canada is because pretty much every every Frenchman I know was rooting for their French brethren in Canada to beat to beat Argentina. So that would be that was the that was the reference there. Yeah. I'm excited about the America's
Rob GalbraithCup problem, man. I I gotta be excited about the whole territory. Yeah. James, I don't know if you you missed prior to jumping on the call, but Jan is now a a US citizen. So he can suffer with us to not even make it to the elimination. Yeah. We did.
James BenhamI know. We did. By the way, congratulations on your citizenship. I don't think I said that, so I'm super excited for you. The yeah. You can you can root for a team that doesn't make it to any playoffs.
Rob GalbraithDefinitely going down and weight glass, Jan. That was a bad move. Great country, bad soccer team.
James BenhamYeah. Yeah. Yeah. We we got we got a long way to go. You know? Anyway, awesome. Well, thanks for the time. And, obviously, to our listeners out in listener land, thank you for listening to this episode of the InsurTech Geek podcast, our discussion with Yann Barbarroux from Autonomy. Thanks, Jan. The InsurTech Geek podcast is all about technology that's transforming and disrupting the insurance world. I've been your host, James Benham. That's jamesbenham.com with co host Rob Galbraith at endofinsurance dot com. We're taking you on a journey through insurance tech, so enjoy the ride and geek out.