 YouTube
 Spotify
 Amazon
 iHeart
 Apple
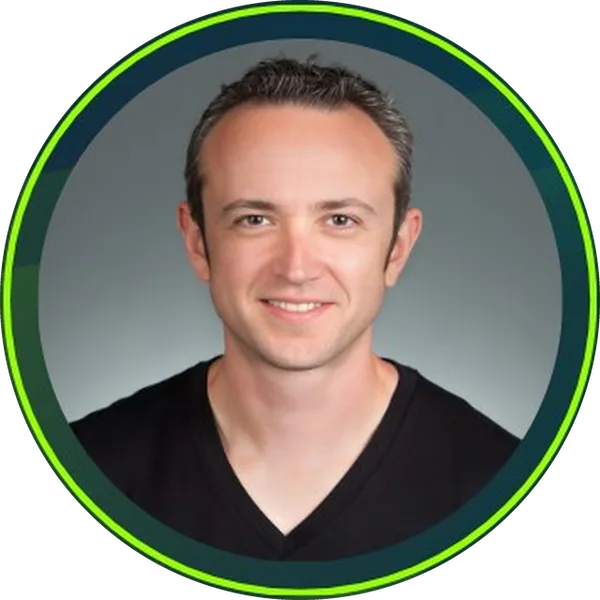
Dan Bratshpis
Dan Bratshpis is CEO and Co-founder of INSHUR, a digital-first commercial auto insurance platform embedded into gig-economy platforms including Uber, Amazon, and DoorDash. He started his career in equities trading at Lehman Brothers before pivoting to insurance after identifying a massive underserved market among app-based rideshare and delivery drivers. Today INSHUR operates across 50 US states and the UK with a focus on usage-based, data-led commercial auto coverage.
In Episode 173 of the InsurTech Geek Podcast, Dan Bratshpis - CEO and co-founder of INSHUR - joins host Rob Galbraith to share how his background in technology, finance, and insurance led him to rethink commercial auto coverage for the modern mobility economy. From his days on Wall Street to building one of the leading embedded insurance platforms for Uber, Amazon, and DoorDash, Dan explains why traditional insurance models fall short for gig workers - and what a truly usage-based, data-led approach looks like in practice.
The full episode
Press play for the whole conversation.

From Cab Rides to Cloud APIs: The Origin Story of INSHUR
Dan Bratshpis didn't set out to build an insurance company. After a career in equities trading at Lehman Brothers - later acquired by Barclays and then Bank of America - he found himself evaluating a family member's insurance agency in New York that catered to immigrant taxi and rideshare drivers. What he found surprised him: a massive, underserved market still operating on paper forms and phone calls in an era when Uber drivers were expecting app-based everything.
The founding thesis of INSHUR was straightforward but ambitious: bring digital transparency and fair pricing to commercial auto insurance for the emerging class of gig-economy drivers. In 2016, Dan and his co-founder launched with a Kayak-style aggregator model. It failed almost immediately. Their pivot strategy: get burner phones, sign up for rideshare promotions, and spend hours riding around New York interviewing drivers about their insurance pain points firsthand. That feedback loop convinced them to abandon the aggregator model and become an MGA - building their own underwriting capability, their own pricing, and eventually their own claims organization.
Today INSHUR operates across 50 US states and the UK, and has expanded from rideshare into last-mile delivery, car-share, and emerging autonomous vehicle coverage - all rooted in the same founding principle: insurance should work the way customers actually live.
"We launched the app and we thought, OK, amazing - we're going to have thousands of signups. And it's just crickets."
Dan Bratshpis
The Platform Playbook: Embedding Insurance Into Uber, Amazon, and DoorDash
INSHUR's defining strategic move wasn't a product innovation - it was a distribution one. Rather than acquiring customers directly, the company chose to embed itself into the onboarding journeys of major gig-economy platforms. When a new driver signs up for Uber in the US or UK, or when an Amazon Flex delivery driver activates their account, INSHUR's coverage is integrated seamlessly into that process. The platform handles the acquisition. INSHUR handles the risk.
The model creates a symbiotic relationship that's hard for traditional insurers to replicate. Platforms get proof of coverage in real time, reducing friction in their driver activation pipelines. INSHUR gets access to behavioral and operational data - trip counts, active hours, delivery volumes - that enables more precise underwriting than a traditional annual policy could ever achieve.
When COVID-19 collapsed rideshare demand in 2020, INSHUR's platform-first approach proved its resilience. As their driver customers pivoted from rideshare to delivery, INSHUR followed - launching last-mile delivery products and securing partnerships with Amazon and DoorDash. What might have been a fatal blow became a strategic expansion.
"We get access to a lot of alternative data. We use that data to price and underwrite in new ways."
Dan Bratshpis
What Autonomous Vehicles Mean for Commercial Auto Insurance
Dan Bratshpis is thinking about something most commercial auto insurers aren't: what happens when the thing being insured rarely causes accidents? Autonomous vehicles don't text and drive. They don't get tired. And while they're not infallible today, the trend is clear - frequency of accidents will drop as AVs proliferate.
For an industry that has historically priced commercial auto around the assumption of human error, the implications are significant. At INSHUR, the opportunity is being pursued from a different angle: coverage not just for the AV itself in operation, but for the support ecosystem surrounding it - maintenance, cleaning, repair, and downtime. These are risks that exist now and will grow alongside the AV fleet, but for which standard commercial products don't yet exist.
The broader lesson is one of proactive adaptation. Those who have already built the flexibility - usage-based billing systems, embedded distribution channels, proprietary claims infrastructure - will be best positioned to navigate the shift when AV penetration forces a reckoning across the commercial auto market.
"The frequency will certainly go down. And I think the insurance industry hasn't really moved quick enough to develop those products."
Dan Bratshpis
Key Takeaways
Embedded distribution changes everything: INSHUR's platform partnerships with Uber, Amazon, and DoorDash remove acquisition friction and provide real-time behavioral data - enabling underwriting accuracy that traditional annual policies simply can't match.
Usage-based insurance is a necessity, not a feature: For gig workers living paycheck to paycheck, flexible pay-per-use coverage is the difference between being insured and not. Annual policies don't fit non-traditional work patterns.
Claims infrastructure is the real competitive moat: INSHUR's decision to build its claims organization in-house turned a cost center into a core differentiator - because when something goes wrong, claims IS the product.
Autonomous vehicles will reshape commercial auto pricing: The carriers who haven't already built flexible cost structures and usage-based products will face existential pressure when AV penetration drives down accident frequency at scale.
The full transcript
Transcribed automatically from the episode audio, so some names and terms may be misheard.
Rob GalbraithAnd we are back for another episode, recording in early twenty twenty six of the InsurTech Geek podcast. I am your solo host today, Rob Galbraith, typically the copilot, but unfortunately James is not available to join us for this fantastic conversation with Dan Bratshpis from Insure. But Dan, we're happy to have you on board and look forward to a fantastic conversation today. As we noted, I am wearing a nice t shirt here in it's not sunny San Antonio, but it is warm. You are a bit bundled up in New York City.
So how are you doing, Dan? Welcome to the show, and tell us a little bit about the weather today there.
Dan BratshpisThanks, Rob. Thanks for having me on. Yeah. I'm a little bit jealous of your T shirt. It's definitely a bit colder in New York, but, yeah, doing great today. Looking forward to this conversation.
Rob GalbraithFantastic. Well, we're thrilled to have you on board. You are one of the the OGs of this kind of Insurtech movement, and we'll get into you and your career. But first, tell us a little bit about yourself. Where were you born and raised? And I don't know if you had a career aspiration to start a a successful InsurTech, as as you, were growing up. I'm guessing not, and you might have had some other early ideas, as a youngster.
Dan BratshpisOkay. Let's see. So I was born in, The Soviet Union in Moscow. I came to The US as a as a kid, with my family. And I I sort of grew up in, Central New Jersey around the New York City area. So that's I've been I've been around the New York City, kind of metro area for most of my life. When I was a when I was a kid, my grandfather was actually a pilot, for Aeroflot, Russia's largest, airline. I always wanted to be a pilot, but that didn't happen.
So I I chose insurance instead.
Rob GalbraithNow did you ever take any lessons, or or you just that was a dream and never That was just the childhood thing. Yeah. Well, you ever want to live out those dreams through James Benham, I'm sure he can tell you all about his flying adventures. I believe his family was into flying as well and kind of passed that down. So kind of interesting. I'm very happy to just ride along in the back and put on my AirPods and not worry too much about where this thing is going or hopefully get to get there on time.
So I see that you went to Cornell. This is actually where my father went and I don't know if you're familiar with the character of Andy Dwyer in The Office that is a proud Cornell Of of course. Teased for that quite a bit. So how did you find your time at Cornell?
Dan BratshpisIt was amazing. Still have a lot of friends. I met my wife there. You know, we've been back several times. My kids have been back there. Actually, my my nephew goes there now as well, so it's it's a great place. It's kind of in the middle of nowhere. At the time, I didn't appreciate it much, but I certainly do now, so it's a great environment.
Rob GalbraithYeah. That area of Upstate New York is very beautiful. I've got some family up there. Addition, my father graduating from Cornell. My grandfather was the dean of engineering for many years at Syracuse University. So we would go visit them in the summer months typically and had been to Ithaca a couple of times and it is an absolutely gorgeous
Dan Bratshpiscampus. If anybody ever finds themselves in the area. That's your neat T shirt dude. Ithaca's gorgeous. I don't know if you've ever seen that, but there's a lot of gorgeous and waterfalls in Ithaca. So there's a green Ithaca's gorgeous shirt. Maybe I'll get that for you. Oh, that would be fantastic. Yeah, that would be fantastic.
Rob GalbraithSo yeah, and it was fun walking around with my fairly stoic father on campus and him reminiscing about some of his college age hijinks. So that was quite fun. I think there was something about sledding on some of the cafeteria trays and whatnot.
Dan BratshpisThat was my Yeah.
Rob GalbraithSo after that, you started kind of in the financial services industry with Merrill Lynch, and then you went to TFG Limited. Flywheel, spent a year, and then in February 2016, you started Insure. So maybe you can just kind of walk us through your career prior to Insure. What did you learn? What skills did you gain? And how did you kind of end up as the co founder of Ventura?
Dan BratshpisSure. Yeah, so started my career on Wall Street at the time in technology and spent a bit of time at different areas around equities trading. So it was actually kind of an interesting time because when I joined, you know, human traders were still very much at the heart of the New York Stock Exchange trading, throwing tickets around. And when I left, it was very much kind of algorithmic trading and and high frequency kinda hedge funds trying to collocate as quickly as close as possible to to the exchanges.
So definitely saw, like, a disruption and an evolution of an industry that I think is analogous to what we're seeing in insurance now as well. So, yeah, I spent a number of years there. We were eventually acquired by Bank of America. And then I sort of got into insurance by accident. As I mentioned, I come from an immigrant background. A lot of my family has kind of done menial jobs and, you know, driven a cab for, to to get to the American dream. And, someone in my family invested in a insurance agency in New York that catered to, for higher transportation risks.
And I came just to sort of evaluate like what, what, what insurance was all about and can technology sort of make a difference here. And my eyes were sort of open to just how big the insurance industry was. How much I think technology has sort of passed it by over the last, like ten years or so, and just how big the opportunity was. And so the idea behind co founding insurer was, you know, there was this immigrant class of and Uber and Lyft drivers. There was a new type of risk emerging.
A lot of them were millennials. A lot of them were looking for digital experience and what we, what the market had to offer at the time was very much, you know, analog paper based. And so my cofounder and I decided to do something about that. And that was that was really the impetus of of ensure we wanted to give transparency around the process, the pricing. There was a lot of distrust between a lot of these immigrants and the the brokers. And so that's what we were looking to achieve.
My career, I spent a couple of years at Flywheel, which was at the time sort of competitor to Uber. So got a, got a taste of the startup bug, before, before starting insure. And so, that's, that's, that's how the, the initial idea kind of sparked.
Rob GalbraithSo, I know, in talking with a lot of, founders and and innovators, sometimes it can be relatively easy and I don't want to underestimate that but to identify a problem, right? Or to identify like there's a gap in the market here for this particular opportunity. But whatever the initial solution that folks come up with is usually wrong and it takes kind of several iterations, right? And there's come to this race before you run out of money, run out of ideas, right, to try to execute on that.
And even if the technology piece is good, right, the distribution part, marketing part, etcetera, it can be a challenge. It's not just about the tech tech is at the core, right? So maybe you can talk a little bit about what was your initial idea and then how did you have to iterate or evolve in shore over time in those early years?
Dan BratshpisYeah, it's a great point. So, I think our hypothesis was, hey, we'll build this Expedia search engine that allowed these newer rideshare drivers in New York to get a quote by policy. We'll go out there. We'll make partnerships with all these different insurance companies. We'll collect our commission. The customers will be happy. And what we actually learned is it was very difficult to partner with traditional insurance companies, very difficult to kinda get the pricing and underwriting to align with this, like, digital experience. And, ultimately, it was very difficult to acquire customers.
You know, there's there's a couple of funny anecdotes I could share with you. In the early days, we launched the app and we thought, okay. Amazing. Like, we're gonna have thousands of sign ups, and you're just like you're waiting day in, day out or like and it's crickets. Right? So I remember I don't know if you remember Uber and Lyft were having promotions where they'd give you, like, I don't know, 20 worth of free rides. And one of the things my my cofounder and I would do is, like, try to talk to these customers and identify what their pain points were in insurance.
It was kind of tough to find these folks. Right? And so what we do is we get burner phones, sign up with Uber and Lyft, get a couple of free rides and like just go around the block talking to these, rideshare drivers just to try to understand what, you know, what pain they sort of felt and understand their, their kind of sentiment as well. But I you're absolutely right. Like, I think the initial vision of like, hey, this, you know, Expedia, Kayak, broker aggregator model turned out to be completely, untenable.
And we we had to pivot and become an MGA, and we learned what a claim was, what underwriting it was, what, you know, making a underwriting profit was. And so it's, definitely, a roller coaster ride of of learning.
Rob GalbraithAnd I know, you know, one key point I think that you wanted to make for our audience is that technology is kind of how you deliver the insurance, but the insurance is still the product and still the most important part to the success of any insure tech.
Dan BratshpisYeah, absolutely. I mean, I think at the end of the day, all insure techs are distributing, you know, a contract, a piece of paper that promises to pay a claim. And, you know, I think the insurance industry has been at the forefront of lot of innovation when it comes to pricing and underwriting and distribution and claims management as well. And I think, technology is an enabler to do things differently, do things better. We're excited about embedding our products into different partners and making things more flexible to the use of usage based tech than telematics.
But at the end of the day, like, think the the core business really is around understanding the the nuts and bolts of of what the insurance industry has really been about for the last hundred years.
Rob GalbraithSo talking about the early days of insurer, like how have you grown and expanded over time? Maybe you can kind of catch our audience up to speed with those early days to where you are currently?
Dan BratshpisYeah. Sure. So started in New York. That was our initial market. As I mentioned, we sort of pivoted from this, kayak model to become an MGA. So we learned we learned what, you know, become an MGA is all about, getting the trust of your capacity partners, being learning how to price and underwrite and and distribute products yourself. So that that was something we developed in 2018. We we started to partner with platforms, and that that is now kind of at the at the core of our distribution strategy.
So Uber's been an important partner for us on the distribution side. We then expanded to The UK market. So we launched a rideshare commercial auto product for for rideshare drivers in the London market and the rest of The UK as well, And that's now a big big part of the business. And Ebers helped us distribute that as well. We learned at you know, in very early days, we learned that claims is kind of at the heart of of insurance. Right? It's sort of like, the the way I like to describe it is it's kinda like the guts of insurance, sort of the you know, how the sausage is made in insurance.
Like, no one really wants to understand how it's made, but it's actually like that is the product that that we're offering is, you know, when something bad happens, we we make sure that we make it right. And so we we decided to build our own claims organization because we found that working with TPAs was pretty painful. And that's that's a pretty big part of the business now. We have TPA businesses on both sides of the Atlantic. And so, eventually, we also expanded into Mainland Europe as well.
COVID hits. I don't know if you remember what what COVID was like, but nobody was taking rideshare rides. And so our our business, literally went off a cliff in in a matter of months. And what we started to notice is a lot of our customers were doing other types of sharing economy work, doing deliveries, food and parcel. We launched the last mile delivery product, ended up being a blessing in disguise, but at the time, was super, super stressful. So that's we now have partnerships with the likes of Amazon and DoorDash on on the delivery side.
And then in several years back, we actually acquired another MJ business in California, giving us access to the rest of The US. And so we now have a 50 state product when it comes to passenger transportation. We also have products around the the car share industry. So folks that work with platforms like Turo and others to rent out their vehicles, we have a pretty interesting product that I'm happy to dig into. So, yeah, the business today is about 60% US focused, 40% Europe. Claims, as I mentioned, is a big part of the the business.
And the way we like to distribute our products is by partnering with platforms such as Uber and Amazon and DoorDash and others really embedding our products into their onboarding journey. We get access to a lot of alternative data. We use that data to price and underwrite new ways. The platforms get benefits as well. We we provide to them proof of coverage in real time. And it's kind of a symbiotic relationship because we help drive down some of the frictions that their customers may face when procuring insurance.
They get the peace of mind that the coverage is there when they need it. We like to make our products as flexible as possible. We have a lot of usage based products, pay as you go. We have products that are paid by the minute, paid by the delivery and things like that. And then the, you know, underpinning all of that is our our claims organization. So we have Komodo claims, based out of actually not too far from you. Our headquarters is in, in Texas for The US, and we have, we also have a great team out in The UK settling claims, not only for ourselves, but, now third parties as well.
And we're excited about, leveraging a lot of new technologies when it comes to AI and and things like that to make our adjusters much more efficient. And that that's the that's the company today, about 200 folks, split mostly between US and The UK.
Rob GalbraithYeah. That's an amazing, story. Thank you for walking us through, your journey. I'm sure a lot of twists and turns, particularly as you you mentioned COVID, that was definitely kind of where my mind went of, how did they make it through? But yeah, the pivot and it sounds like you came out on the other side much stronger, even though I'm sure those are very trying times. What doesn't kill you makes you stronger. So I'd be remiss if we didn't talk on the Insurtech Geek podcast a little bit about the technology side.
So maybe you can talk a little bit, obviously you articulated that initial vision, Kind of this app, this experience, this kayak, later pivoted towards the MGA business model and becoming more of an embedded play with some of the platform. So maybe you can walk us through, particularly when you talk about having the claims in house versus TPAs, and I'm thinking, well, that means you got to design your own claims system unless you're buying something off the shelf or whatnot. So maybe you can walk us through in parallel to what you did from some of the business twists and turns, some of the big forks in the road from a technology standpoint over the past decade.
Dan BratshpisYeah, sure. So I think the first big decision we sort of needed to make was decide, like, what would be our policy admin system? You know, today, there's actually a lot of great sort of companies that help up and coming startups kind of launch products quickly. When we started, like, your options were sort of like Guidewire and Duck Creek, and we certainly couldn't afford that. So the decision was sort of made for us and we decided to build our core system ourselves. I would say that it it turned out to be a lot more complex than we had envisioned, especially when it comes to satisfying the requirements, not only for The US business, but Europe as well, making it sort of global from the get go, multicurrency, multi tenancy, multicarrier.
And then the added complexity of being able to embed those products, partner with platforms, expose APIs, and transact business that way, and making it super simple. Right? So insurances, you know, you're selling this 100 page contract with a lot of legalese in it, but how do you most people never read that piece of paper. Right? So how do you how do you make it as simple and easy for the customer to understand, you know, what the coverage options are, what it is that they buy, what what it is they need to buy, and, what happens in in the case of a claim.
I think, you know, those are all been areas that we've invested in. Something a little bit, like, newer after COVID, we developed. We focused a lot on on flexibility. A lot of our customers are, you know, immigrants. A lot of them are living paycheck to paycheck. And so affordability and flexibility is definitely, something that we try to solve for. And so we developed a usage based wallet, that embeds with our our partners, and we can price insurance by any number of exposures. So we we could price by the minute.
We could price by the delivery, by the ride. And so that is that that's another area that we've invested in, and we'll we'll continue to roll out those types of products. Actually, you know, having developed the technology, it's the the regulatory side that's really been kind of the challenge of you know, in The US, we're dealing with 50 states and, you know, not every state is open to a lot of these flexible products. We've been experimenting with surplus lines products, and that's allowed us to be a lot more creative in some of the products that we've distributed today.
Rob GalbraithAnd did some of those regulatory challenges lead you to kind of you know, you mentioned kind of the initial start around the the New York City area, but then you talked about going to The UK and then later making this acquisition of the California company that gave you the the full 50 states. I think a lot of people might find that kind of an interesting choice, right, to kind of branch out to Europe and internationally before a full expansion in The US.
Dan BratshpisYeah, it's definitely, I would say, untraditional, but I think everything we do is sort of that traditional. Really, it came out of wanting to solve the needs of our customers and our partners. And so there was an opportunity working with Uber in the London market, and we had a capacity lined up at the time with a global reinsurance, so it it sort of made sense for us to expand. Across The Atlantic, a lot of our engineering talent now sits in The UK, so it made things a little bit easier for us as well.
But, yeah, as as you said, it was a nontraditional path, but, we are we are a global company from the get go.
Rob GalbraithYeah. And then I think about, right, London, I think of London and New York City as being somewhat similar city. I mean, both have their own their own charm and their own beauty. Right? But, just in terms of being large cities, with, like, strong financial and insurance markets and a place that most people don't necessarily own their own car, right, just because of the the cost of, having to to to to store it to ensure the pain of driving yourself around, etcetera. Right? So it does seem like those are two markets that have, some of the greatest needs.
And particularly, you talk about immigrants as well. Right? Both, have a lot of immigrants from all around the world. So I'm just curious, Dan, like, kind of describe your marketplace, and I'm thinking that a lot of these workers aren't working a traditional nine to five, right? And so it's not just that, Okay, I've got some type of commercial audit exposure here or whatnot. So how did maybe thinking about not just the needs, but rhythms of the work itself and how people are going to interact with you when they're going to act with you, how did that maybe change your thinking about how insurance should be designed and delivered?
Dan BratshpisYeah. It's a great question. I think, you know, the the the on demand economy kind of spans personal and commercial exposure. And, you know, most of the products that you see, in the market today are one or the other, and what we what we've been trying to do is kinda meld those two, products together. And so we try to design all of our insurance products to work with our customers. And so I'll give you a couple examples of how we've been able to do that. So in the case of, like, the car share industry, a lot of folks have, you know, acquired one car, and then they buy a second car or third car, and then they kind of rent out those assets on on platform on car sharing platforms.
And, you know, most personal auto insurance, you know, when you call up GEICO and you said, I'd like to add my tenth vehicle, typically they'll ask like, hey. What what's going on here? And so their options are really to buy like a commercial rental car insurance policy, which is super expensive. And the other thing to keep in mind is when those vehicles are rented out to the end consumer, a lot of times there's already commercial coverage that the the platform already provides. And so what we've done is we designed a product that basically covers them for the off rental portion of the before they actually rent out the vehicle.
Super flexible, super inexpensive, and it allows them to kinda get the coverage that they need before it's rented out so that they could do maintenance, you know, repair work, oil changes, things like that. That's one example we have other products that are kind of like the inverse of that. So as an example in The UK, if you are a delivery driver for, you know, platforms such as Amazon flex, which is their kind of bring your own vehicle and do delivery work part time. You know, you typically have a personal auto policy, but you're missing that commercial coverage.
And so we, we sell an insurance policy that's the the inverse of that. So we cover you just when you're doing the delivery work. We price that product based on how many deliveries you've done and the the hours that you've worked. And it's it covers you for the commercial portion of that of that exposure rather than the personal lines product that you probably have from somewhere else. So everything that we do tries to kinda like get the product to work with the customer's way of life.
Rob GalbraithDan, I'm thinking, you know, obviously, I think a lot of people are familiar with ride sharing, with car sharing, more the shared economy, as you mentioned. Some people call it gig economy. And I'm thinking that there's a lot of other platforms out there, not limited to simply vehicles that are out there that probably have their own insurance challenges, their own unique insurance challenges. So I'm just kind of curious, like, do see opportunity there? Have you explored it? Have you had conversations with other folks in this space?
Obviously, I think that traditional kind of nine to five, forty hours a week, we see it in the healthcare industry, right? More and more people are getting it through the marketplace rather than their employer, things like that. So maybe there's some broader shifts in the economy that you're seeing that may lead to opportunities.
Dan BratshpisYeah. I mean, absolutely. I think, you know, I would say wheels is kind of our expertise, our team's expertise, and, you know, a lot of the products and systems that we've designed are around wheels, commercial wheels. But our ambition is really to go much wider than that. And I think there's a ton of opportunity when it comes to, like, if if you're a food delivery company, your prod it's a two sided marketplace, and you have, you know, restaurants that you're doing business with as well that are offering, you know, meals to folks.
So there's certainly an opportunity to expand into other product lines. Same with, you know, retail kind of platforms doing delivery work as well. And, and then we have, like, the up and coming autonomous revolution that that's coming as well that presents a lot of, new opportunities when it comes to embedded products, usage based products, leveraging data in in new ways. So we're excited by that as well.
Rob GalbraithSo where are we with those autonomous vehicles, Dan? I know we had a lot of hype probably ten years ago about the time Insure started, and I know we have some out on the road, but it's still kind of more of something that folks read about today. But you've probably been following develops and the twists and turns in the road, if I use a poor metaphor.
Dan BratshpisSo, yeah, just curious maybe we can share with our audience kinda what's the state of play today as you see it. Well, first of all, like the the product itself is, developing at an incredible pace. I I don't know if you've you've taken a couple of these, vehicles, but it's it's incredible. I own a Tesla. I love it. I I rarely ever drive anymore. And so it's definitely coming, and I think the insurance industry needs to, be prepared for it because these things don't get into accidents nearly as much as humans do.
They don't text and drive. They don't get distracted. You know, do they make mistakes today? Yes. But what I, what I find interesting is like the, the industry is developing in different ways. And so you have some companies that are kind of developing dual use vehicles where, you know, perhaps you will drive at some portion of the time and then, you know, the system will take over fully autonomous. Then there are platforms that are planning just for commercial kinda like rideshare use as well. And there are new opportunities that I think the insurance industry needs to think about.
There's you know, these vehicles, even the ones that are fully autonomous and need and are taking passengers from point a to point b, at the end of the day, they still need to be maintained, repaired, cleaned, car wash, and things like that. And so there are a number of these companies that are now in that space, and they need new insurance products that frankly don't exist yet. I think the insurance industry hasn't hasn't really, like, moved quick enough to to develop those products, and that's something that we're working on as well.
And so it's gonna be certainly an interesting space. I think auto is one of the largest lines of premium generations for for the globe, for the insurance industry. And I think that's that's about to change because the frequency and the severity severity may may go up, but frequency certainly will go down. And so I'm excited to see what, we're able to come up with for this upper coping industry.
Rob GalbraithYeah. I'm excited to hear that you're on top of this and thinking about this because I know I was kind of theorizing several years ago and and wrote it a little bit about it in my book, the end of insurance as we know it about, you know, if you think about most of the expenses, right, that have been built up over time for, right, most of the leaders in the auto insurance industry space, particularly personal auto, more familiar with than commercial auto, but I imagine it's similar, you know, they've been around for decades, right?
And the basis of the model hasn't changed very much. You've got this requirement. You've got to have auto insurance. Of course, you have losses and those can vary and you probably have some LAE that varies as well. But most of the other expenses, you know, are covering, right, commissions or salaries or technology, you know, they're more fixed expenses. And so if your revenue drops by, you know, 50% because this huge drop in frequencies you kind of mentioned, right? What does this do for your bottle if you're typically running at a 25% expense ratio, you know, that may not that may spike if you don't do anything from the expense side to change your operations.
And I think that type of like radical downsizing or streamlining or whatever folks have to do, they're going to be very challenged just adapting to the marketplace and then really adapting their current business models to fit the new reality.
Dan BratshpisYeah, 100%. I think, again, this is where technology and AI can be a force of good, right? It can get efficiencies that you otherwise wouldn't be able to get from just human based talent, and that's something that we at Insure have been very excited about investing a lot into as well.
Rob GalbraithSo Dan, let's wrap up with little bit of that future vision on where technology is headed. I know it's probably enabled more flexible, more data driven insurance models. Obviously, we've talked on this podcast about the ability to actually fully leverage unstructured data in a way that just wasn't possible. How do you kind of see the commercial auto, and I don't want to even limit it to that, but start there evolving over the next few years.
Dan BratshpisYeah. Absolutely. So I think, like, it all starts with we think the world is on demand. We get food on demand, rides on demand, packages, services. Soon, we're gonna get autonomous vehicles on demand, and we're actually getting it today as well. And insurance is a really big part of protecting this this new new economy. And so we're excited to build flexible, affordable, data led insurance products that work with our customers' needs, And we're gonna continue doing that across all of our markets and all of our product lines, and we're excited about where this industry goes next.
Rob GalbraithYeah. That's exciting. I don't know, Dan, if you've ever heard about the ten ten rule, but this idea that it kind of takes ten years to kind of get started to stabilize and then another ten kind of for the exponential growth phase. And so I hope that might be in your future knowing that you're hitting as we're in 2026, rapidly approaching your ten year anniversary at Insurer.
Dan BratshpisYeah. I appreciate it. Thanks for that, and thanks for having me on. This has been an amazing conversation.
Rob GalbraithFantastic. Well, a big thank you today to our guest Dan Brachbiss from Ensure. Glad to have you on the program. It was a pleasure to hear your story and your journey. No thanks to James because he didn't show for this episode, but of course he'll be back shortly as we record future episodes. And thank you, most important, our loyal audience for tuning in today to Geek Out for our interview with Dan Brechbis from Insure. See you next time. The Insertech Geek Podcast is all about technology that's transforming and disrupting the insurance world.
Hosted by James Benham at jamesbenham.com