 YouTube
 Spotify
 Amazon
 iHeart
 Apple
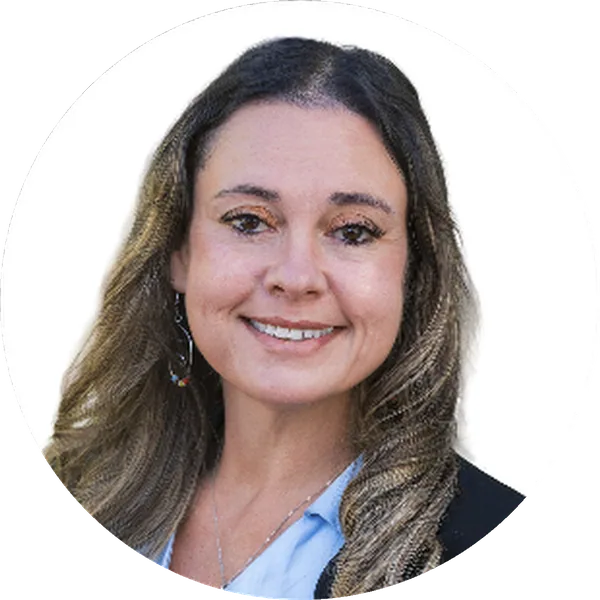
Carrie Coronado
Carrie Coronado, Director, Workers' Compensation Underwriting and Data Analytics Manager at Care West Insurance Company, joins host Rob Galbraith to talk about how data, analytics and technology are changing workers' compensation underwriting. Drawing on more than two decades in insurance and nearly 18 years at Care West, Carrie explains why analytics should be a tool and never a replacement for the underwriter, how she proved its value to her executive team, where AI can genuinely help a statutory line like workers' comp, and why the industry needs to rethink how it trains the next generation of underwriters.
The full episode
Press play for the whole conversation.

A Backgammon Briefcase and a Binder Full of Guidelines
Carrie grew up in the Sacramento area. Her mom still tells the story of her walking around with a backgammon game as if it were a briefcase, so the businesswoman part was always there. She also spent time considering microbiology and studying viruses. Only a few years ago did she realize she had found a way to do the same kind of close analysis on insurance, which brought her love of science full circle.
Her way in was a call center job for an auto insurance agency while she was studying for an entry level role in the medical field. She was assigned a project to go through every carrier's underwriting guidelines, in actual binders, and update them. What fascinated her was how the guidelines were the same but different from one carrier to the next. Why did one carrier care more about seatbelt violations while another cared about tires? What made each one's secret sauce? She switched her major to business and has been in insurance ever since.
After the call center came an MGU, where she developed an appetite for standards and underwriting practice, and then an agency, where she worked mostly with contractors through the 2008 construction downturn. That stretch taught her she is more of an advocate for the carrier than for the sale. Care West recruited her as an underwriting assistant in 2008, which honestly felt like a step down, but it was a carrier role. Today she likes to walk new staff past every desk she has sat at, from the tiniest assistant desk to the corner director's office.
Leaning Into Data Before It Was Obvious
In 2019 The Institutes launched the AIDA designation, Associate in Insurance Data Analytics. Carrie already held her ARM, she was in her thirties with a lot of career ahead of her, and she told her boss that if data and analytics were going to be a big part of underwriting, she needed to dive in. Since then her trajectory has been about combining the two disciplines.
Rob relates. He started as an economist, worked as a research assistant at the Federal Reserve Board, and moved into pricing at USAA before a vice president standing up the company's first underwriting data analytics team pulled him in. One of his first projects questioned a long standing rule that USAA would not insure a member's second home unless it also insured the primary home. The analysis showed second homes have lower frequency but higher severity, because a leak or roof damage can go undiscovered for months, and the loss costs came out almost identical. The guideline went away.
You Cannot Form Your Way Out of Dishonesty
Workers' compensation has a property that makes analytics especially valuable. In a liability policy, if a risk turns out to be different from what was disclosed, you can add an exclusion. Comp is statutory.
If an applicant says they have no height exposure and someone falls off a ladder, the claim gets paid, whether the applicant was dishonest or simply misunderstood the question. That is exactly why data helps: it can surface correlations and insights that a supplemental application never will.
Carrie's goal throughout her time at Care West has been to change how people think about analytics, as a tool and not a replacement. Because comp is so statutory, it does not lend itself easily to straight through processing. A person still has to validate that the story is right, and the data supports the gut pricing feel of the underwriter working the desk.
"You cannot form your way out of dishonesty."
Carrie Coronado
Letting the Data Prove You Wrong
After years with analytics profiles in place, Care West can now look back and see where it was wrong. The model said a class of business could be priced successfully for four years, the team disagreed for four years, and four years later the results showed they should have been writing it all along. That is a powerful message, Carrie says, both for underwriters and for the executive team.
It can even take guilt off underwriters. Someone raised on strict rules feels wrong writing an account the old guideline would have declined. When analytics shows the account performs better than similar risks, it can give them permission. Rob adds the other side of the coin: large loss reviews tend to make underwriters more conservative over time, but a large loss is a single data point, important yet still one data point against thousands of accounts where nothing happened.
Care West underwrites every account individually, which Carrie is proud of as a middle market carrier. The real power shows up when a broker is pushing for a couple of points on rate, the underwriter is at their wits' end, and the model says the risk performs better than its peers on frequency, severity or payroll. You write it, you win it, and it stays profitable for five years. Her inspiration was Capital One finding borrowers nobody was serving and building a successful credit model around them. Her first question was how to apply that to insurance and find the small businesses the market is not recognizing.
Analytics is also reaching claims: spotting the indicators that a claim will develop into a large loss, and evaluating which medical providers get injured workers healthy and back to work fastest. That, she says, is the why of workers' comp: making a person whole so they can take care of their family and get back to their job.
Making Innovation Measurable
Measuring innovation is one of the hardest things an insurance carrier does. Care West had an advantage: as early adopters, the analytics provider needed their data to build its consortium model, so the cost was low and trying it was an easy sell. To keep it going, Carrie made it measurable. She tracked the loss ratio and could show that the model saved two points on a 25 million dollar book, while the tool cost 18,000 dollars a year. Who, she asks, is being hurt by that?
The model has always been treated as a tool, not a pricing engine, partly because of how a Department of Insurance views a black box and partly because it was never meant to replace an underwriter. That made it far less threatening to the team, and the same change management conversation is now happening with AI. Just the day before the recording, a long time team member asked her what would happen to them if Care West got into AI.
The plan is to remove the redundancy and the daily grind and find each person's next value proposition. Care West likes to say it is in the business of doing good, and if you stay people centric, Carrie believes, the rest works itself out.
"We're going to elevate you. That's the answer."
Carrie Coronado
Where AI Helps Workers' Comp Underwriting
Rob had just come back from an underwriting conference that could have been called an AI conference. For Carrie, the game changer is the fast gathering and validation of information. Instead of sending underwriters down five different Google searches, put everything in front of them at the start of the review. Use analytics to learn what your most frequently asked questions are, what your business drivers are, and what your best underwriters look at that nobody else does, then package it so they can make informed decisions faster.
Anyone who has worked an agency desk knows that once a prospect is on the phone and willing to share payroll, you need an answer before they lose interest. Comp underwriting has long relied on back and forth and mammoth question lists. Care West's values, paying benefits, protecting wealth and helping people build wealth, all depend on doing that better. Rob agrees that the consensus is to automate the data gathering and leave the judgment, the insight and the broker conversation to the underwriter, and notes that plenty of low hanging fruit remains, like people still retyping information from one screen into another.
Carrie's example is loss runs. Anyone who has received 60 pages of them knows the value of a program that can read them, transcribe them into Excel and tell you what share of 175 claims are cumulative trauma, a job that used to take her hours of tally marks. Her concern is what comes next. She knows to ask the AI for that analysis because she did the job. Models should learn, but at what speed? If one severe zip line claim teaches a model to stop writing anything with zip lines, a whole camp program disappears.
"It's a lot more about scaling than actually reducing your staff."
Carrie Coronado
"There's going to be a lot of managing the bots."
Carrie Coronado
Training the Next Generation of Underwriters
Underwriting has always been an apprenticeship, and Rob asks what happens to the first five to ten years of a career when routine tasks are automated. Carrie remembers the same fear when file clerks disappeared and the industry went paperless. Curious newcomers used to walk up to an underwriter and ask what an unfamiliar form did, and that curiosity is what makes a great underwriter. She does not claim to have all the answers. She tells her team she has never done this before either, so they will figure it out together, and she is building an accelerated associate underwriter path that starts close to an assistant role, monitors the technology and moves early into renewal underwriting.
In her office hangs a black and white photo of a typing pool from the 1940s, a reminder that all of that work now fits inside her tablet, and people are still working.
Video AI, Stretching Programs, and Adoption Without Blinders
Looking five to ten years out, Carrie is most interested in video AI. It can see far more minute detail than the human eye: a subtle change in a skilled nursing resident's gait that raises the risk of a fall, or how a manufacturing process really runs. It could finally let carriers reward best in class employers with visual proof, and even test long held assumptions such as whether stretching programs actually work.
She also sees competing personalities in tech adoption. The industry talks a lot about veterans who distrust technology, and much less about newcomers who expect everything to work like their bank app. Rob shares a story about a Wall Street bank that hired AI savvy graduates and found their critical thinking needed extra training. Carrie's answer is to keep people at the center.
Validate people, especially the tech forward ones, and make sure they know they can challenge the machine: just because the computer says something is right does not mean it feels right. Create that kind of space, she says, and you will get better results from every new technology you apply.
"We insure people. And these are real businesses. They're not just numbers in a spreadsheet."
Carrie Coronado
Key Takeaways
The full transcript
Transcribed automatically from the episode audio, so some names and terms may be misheard.
Rob GalbraithOn this episode of the InsurTech Geek podcast, we explore workers' compensation, data-driven underwriting, and the evolving role of technology, with Carrie Coronado, Director, Workers' Compensation, Underwriting, and Data Analytics Manager at Care West Insurance Company. And we are here again on another episode of the InsurTech Geek podcast. This is your host, Rob Galbraith. I am flying solo. We have no James for this episode, sadly. but it is during ITC week, so a very busy time that we are recording this. Joining us today and also traveling, coming to us from Scottsdale, Arizona, where she will be flying back to her hometown area of Sacramento, California later today, is Carrie Coronado.
Welcome, Carrie.
Carrie CoronadoThank you, Rob. I'm glad to be here.
Rob GalbraithSo thrilled to have you, and I know this is your very first time as a podcast guest, So we are fantastic to have you on our show for the very first time.
Carrie CoronadoThis may be the first of many who knows.
Rob GalbraithAnd I know you've done a lot of other kind of work in the past to kind of from a promotional get the word out, but first, first time on a podcast. So we'll definitely be kind. And I know that our listeners are going to gain a lot from your insights. So thank you so much for, for joining us on the InsurTech Geek podcast. So, Carrie, we get started typically by just learning a little bit about you to start with. And I guess we always start with the question of when you were a little girl growing up, did you want to become an insurance professional or did you have some other career aspirations?
And where did you grow up?
Carrie CoronadoYeah, I did grow up in the Sacramento area. My mom will tell a story that I used to walk around with the backgammon game like it was a briefcase. So I think I did always want to be a business woman, but I also spent a little bit of time, um, considering going into microbiology, like, um, studying viruses and things like that. And it wasn't until maybe three or so years ago that I realized that I found a way to like microanalyze insurance as well. So it comes a bit full circle.
So I think I've found where I'm supposed to be based on the combination of my backgammon briefcase and my love of science.
Rob GalbraithNow, I love the backgammon briefcase. That is fantastic. So did you also try to dress up maybe a little bit more than some of the other kids in school, or was it more the backgammon case that kind of gave it away?
Carrie CoronadoNo, I mean, I've always loved a blazer from a young age, so yes.
Rob Galbraithyeah i think there was a time there that uh i decided that uh you know your your uh hometown that has the sacramento kings right the nba team we've got our only professional franchise of san antonio spur so um i liked the nba draft look where i would have the the business shirt tie and then the the baseball cap kind of look i don't know it's very strange you know but i thought it i look good in middle school what can i say oh great um so um yeah once you uh graduated like tell us a little bit about kind of your educational background and how you got started in the industry
Carrie Coronadoyeah i was in college and studying some you know entry-level nursing type things kind of getting started in that part of the medical field. And I ended up taking a job at a call center for auto insurance. And I was doing really well there. And they assigned me a project to go through all the underwriting guidelines and update them with the carrier's information. And of course, this is like when we were using binders for this, there was no online database for that. So it really just fascinated me how the same but different the guidelines were by the different carriers and like what makes that their secret sauce why do they care more about seat belt violations than this carrier cares about tires like what how are they developing that and um and I soon just decided like that this is for me and just switched my major to business and um been I've been in insurance ever since so like many of us you just kind of trip and fall right into an insurance company yeah
Rob Galbraithyeah absolutely oh so many great stories but at least you had a little bit more a direct path than some of the the art history and philosophy majors I've met over the years So you've been with Care West since 2008. How did you start working with them? And what are some of the roles that you've had over the past 18 years?
Carrie CoronadoYeah, I was working at an agency. I was doing sales. I was having mild success at it. but um that this is 2008 so obviously a big um construction um downturn in the economy and i was working primarily with contractors and so um needed something a little more stable Care West was hiring i was recruited as an underwriting assistant which felt a little bit like a step down to be honest but it was a carrier position so i said you know this is right for me and one of the things that I learned while I was at the agency is that I'm more of an advocate for the carrier than I am for the direct sales part of it.
So it was really back to home for me to be at a carrier in between the call center, the agency and Care West, I was at MGU. And so I got more of an appetite for the standards and practices and underwriting. So it was, it was a return back to that for me going to Care West and since then i like to take sometimes staff around and show them every desk i've sat at because i started at the tiniest desk as an assistant and now i'm in you know the corner director's office and i've done most things in between um in 2019 is when the the institutes started the AIDA program.
So that was the associate insurance data analytics designation. And I'd done the ARM at that point. And I was talking to my boss and I'm, you know, in my thirties at this time. And like, I've got a lot of career left. And if data and analytics is going to be a big part of underwriting, I needed to dive into that. And so that's when I really started focusing on, um, analytics and modeling and how those things relate to underwriting. And that's kind of been my trajectory since then is to really combine the two.
Rob GalbraithI, I love that. And, and I can relate a little bit, Carrie. So my background is I was an economics major. Um, I started my career at the federal reserve board, uh, working as a research assistant for like PhD economists, right. To help set interests out and then move to, and I grew up in Michigan, went to Michigan state. Um, then, uh, after two and a half years in DC, I moved down here, uh, to be with my college sweetheart now ex-wife, number one. So I will bore with all that stories.
Um, but, um, so I was looking to catch on and I caught on with USAA where I ultimately spent, um, 20 years of my career. And so I kind of bounced around a little bit in a couple of different roles, um, and found my way to be a pricing analyst, but I couldn't pass the, the actuarial exams. I was over five, not that good at math.
Carrie CoronadoI was good at math,
Rob Galbraithbut not that good at math. And so in 2005, I really caught a break in that, um, I, the, the underwriting team at that time was standing up, uh, a data analytics team for the first time. So it was actually pretty early. And so, um, there was a vice president that was going to be, you know, leading the, the effort. And he kind of knew, I think a little bit about my background and not having an actual science degree or whatnot, you know, so kind of good with data, but struggling.
And so he said, like, you know, you already have your CPCU, which I had gotten in like 2004, got a recommendation just to learn more about the insurance industry. And so it was perfect. So that was my entry to underwriting where I spent 15 years, 10 in a leadership position. And I always valued that because um you know some of the first uh projects that i was on was you know we have this underwriting guideline you were talking about you know we will not insure a secondary home unless we insure the person's primary home and he's like you know that's been a rule forever but you know does that actually make sense and so we did the analysis and then we we realized ultimately that the risk profile was different a secondary home was much less frequency right because you're not there that often but much higher severity because if something does happen while you're not there a water leak or something like that then it could be you know or damage to the roof hail damage and then it's been undiscovered for months right all of a sudden you've got some water seepage from from following rain events or snow or something like that and so from a from a loss cost standpoint they were actually almost identical and so we made some adjustments to our pricing whatnot we removed that guideline and we went through a whole bunch of others kind of from that data and analytic um lens and so it was interesting then leading some of the the underwriters that were managing individual accounts, talking to the USAA members and listening to some of those calls and having to take some of the escalation calls.
And then even later managing our property guidelines for homeowners, for renters, for what we call valuable personal property, jewelry and things like that. Just because I had never grown up as that underwriting assistant or started from that background that most of the other people did. So it's kind of cool to have that underwriting lens and that data analytical lens. I love that you kind of came to it almost from the opposite way that I did. So I am curious, like, you know, given your long tenure at Care West, you've probably seen a lot of changes in the underwriting guidelines.
So what are some of those biggest changes you've seen and how underwriters risk or how underwriters evaluate risk and make decisions, particularly as data and technology has become more central in the process.
Carrie CoronadoYeah. With workers' compensation, there's always the concern that you cannot form your way out of dishonesty, right? So if somebody indicates to you that they don't have a height exposure and you write the account and someone falls off a ladder, you still have to pay the claim. It doesn't matter if they were either dishonest or misunderstood the question or any of those things. Whereas in a liability, you could say, okay, well, we're going to put a six foot height exclusion on there. And if you have an overspray claim or something like that, we're not going to pay it.
So the statutory nature of workers comp, I think lends very well to the use of data analytics because it can find correlations and insights that you can't maybe see on a supplemental application or on a ACORD application. It's been my goal over my time there to just change the way people think about analytics as a tool and not a replacement um again because it is so statutory comp doesn't lend as easily to straight through processing or those kind of um submission um guidelines you really you really do need a person validating that we're getting the right story and um and using the data to kind of support the gut pricing feeling of the underwriter working the desk.
And another growth that we've had in using analytics is that you can now look back historically now that we've had the analytics profiles for so long and you can see where you've really been wrong. Like they've been saying we could price this successfully for four years and we've been disagreeing for four years. And it's proved out that four years later, we should have been writing this all along. And so that's a powerful tool to show not only an underwriter, but also the executive team, right? To your point about the guidelines, like why are we doing this the same way we've always done it?
And I think what you mentioned about the two roles, right? Analytics and underwriting, when you've come from this world of, we never do this, we have a strict guideline on this. Something tells you, okay, well, that's wrong. And if I do that, then you're going to feel guilty about it because you've wired something in your brain. And then to have the analytics part come over and say, actually, you were right and you could have been doing this and you shouldn't feel guilty about it. It can actually support you in a way I think people are scared to allow sometimes unfortunately
Rob Galbraithyeah i love that i think your natural tendency as an underwriter most underwriters is to be kind of risk adverse and there's always that flip side of it right and especially i i don't know about uh you know your experience at Care West but some of the experiences i've had in the past um with underwriters not again not necessarily being the person to make a decision on a particular account but being in meetings with um our claims team doing large large loss reviews, right? And then kind of realizing like, well, what were some of the missed signals that this, you know, could end up in a large loss?
And, you know, some of them are just quite really unfortunate and tragic circumstances and there's not much that we can do. But sometimes when there is some question about, you know, did we not do as much due diligence as we could be? I do think over time, you know, in all reasonable questions and always good dialogue right but it does kind of lend maybe over time just to have that effect where you tend to be like more and more conservative i guess yeah so it's good to counterweight that or to have the large loss is obviously a single data point right so it's an important data point but it's it is just that and so um sometimes from an underlying perspective we were always frustrated it's like well you don't understand like yes that happened on this but we have 10 000 others that the same thing didn't happen right you know what i mean yeah whether it's a limb overhanging a roof or things like that and we were like well if we send an inspector out there for every you know concern about a limb overhang we'd spend so much money on inspections we'd never you know be able to to uh ensure all but like the most high value homes or something like that um so do you have any uh specific examples i'm just curious like where maybe there was like a a guideline that And you don't have to specify, like, you know, in detail, but maybe a philosophy or a change in position on, you know, particular.
Carrie CoronadoYeah, we operate as single account underwriters at Care West. It's something I'm really proud of, actually, because we are a middle market. So every account is getting looked up by a person and whatever story is being told is being heard. And so I think it's not really to say that we've had like an overhaul of like, oh, we used to not write plumbers and now we write plumbers or something like that. More so, what I've found is if you're on the fence, the type of model that we're utilizing is proprietary.
We purchase it from a third party. They use our data and a consortium of data that's like, that's similar, and build a model that way. And so more than anything, when you have that account where you're being pushed, let's say, by the broker for a couple extra points on rate or something. and you're maybe at your wits end with it or you can't really find the validation, but the model is telling you this performs better than like risks in the group historically and by these data points and whether that's frequency or severity or payroll, different metrics.
And then you go and you write that account and you win it and that account's profitable for five years, that's when, you know, there's a real power in, I think, the use of analytics. And for me, it was as simple as my first time hearing this story about Capital One and being able to find a whole group of borrowers who were not being, you know, accessed and building a very successful credit model on that. And how can we apply that to insurance? That was my first question, how do we find these underserved people that aren't being recognized in the marketplace and bring them a product that they need, whether that's small businesses or, you know, again, like I said, plumbers or something like that.
How do you find that correlation and then apply it? And I think that's been the more, it's been a shift in culture and understanding more so than it's been a shift in like underwriting guidelines by definition. There's also this other whole part of analytics that I don't think we talk about enough, but we're also applying this to claims, right? And trying to figure out to your point, what is, what are indicators of development of a large loss? And we're dealing with humans, right? And their health and comorbidities and these kinds of things.
So finding those elements, but also we are applying analytics to the medical provider network and see who's giving the best results and how, what people are getting back to work. And, um, I don't like to get too philosophical about it, but like, that's what we do. That's our why, right. Is to make a person whole and make sure they can take care of their family and get back to their job. And to be able to use analytics in all these different places to find the best results and the speediest recoveries, I think is also a really powerful part of the conversation.
Rob GalbraithI'm so glad you went there because, again, it is easy to get cynical, right? Of people that, whether it be, you know, individual patients or sketchy providers or whatnot, right? That are really trying to to game the system right and so um where the whole point right of workers compensation is to be there right you got hurt at work this wasn't your fault it's not covered by your regular health insurance like we're going to step in and we're going to provide for you and your family to make sure you're interested to take care of to replace the income right so that's not lost and things like that and it is very powerful you know um and i've that people i had the fortune of working at AF Group for two and a half years so that's their specialty is is work comp so i definitely think like it's a um it's a great line to to be in right if you want to make a difference but um yeah it can be challenging right um uh as well so i think finding the right balance there is is fantastic to to hear so i'm curious um Carrie like as you you personally were kind of going down this data and analytics road you mentioned the the designation from the institutes and your belief like i'm gonna guess that not everybody in underwriting at Care West was equally as passionate about data analytics so just from a change management standpoint or introducing like um how did you maybe overcome um skepticism about you know incorporating more data and analytics in the work that the underwriters have been doing at Care West?
Carrie CoronadoYeah, I think measuring innovation is probably one of the most challenging things for an insurance carrier to do. What is the return on investment? Because we were such early adopters, candidly, it was very cheap for us. They needed more data to build the consortium, right? So at that point, they're kind of buying data so it wasn't a hard sell to my executive team for us to just try it and then to take it from that and make it measurable you know what i started doing is obviously measuring the loss ratio and saying okay this saved us two points you know on a 25 million dollar book and we paid $18,000 for the year to have this so who's being hurt by this right Right.
I've always this the whole time that we've been utilizing analytics, considered it a tool and not a pricing model for multiple reasons. I mean, there's also concern with the Department of Insurance and how, you know, you can show what's in your black box and those different things. But it's never been a replacement to an underwriter. And so I think it's less threatening that way. Um, but I can see opportunity and analytics to, um, do some straight through processing and things like that, especially in different lines of coverage.
So I think that the change management is, we're having it right now with AI, right? We're having the same conversation. And what I just yesterday with one of my long-term strong team members, who's, you know, wants to know hey what's going to happen to me um if we get into this ai business and you know we're going to elevate you that's the answer we're going to find something more fun for you to do that that take away some of the redundancy and daily grind that you're dealing with and and find out what your next value proposition is you know um and it i think if you're we always say at CareWash that we are in the business of doing good.
And so if you're in the business of doing good and that's your focus, I think if you stay people-centric, even when you're talking about analytics and AI, that the rest kind of works itself out.
Rob GalbraithI'm so glad you went there with AI because that was my next question. So obviously tons of buzz, tons of hype around AI. I just was at an underwriting conference in Austin a couple of weeks ago. It was an underwriting conference, But you might as well call it an AI conference because it was basically, you know, for for the full two days, like what everybody, every session, every every topic of conversation felt like it revolved around AI, automation, predictive analytics. So when you specifically look at kind of workers comp like underwriting, where do you see technology creating the most meaningful opportunities and where is that experience and judgment of the human underwriter still essential?
Carrie CoronadoYeah, for me, I think the fast gathering of information and then the validation of that information is game changing for us, right? If you can, without being too, you know, proprietary is to say that we're basically, if you can gather all the information and put it in front of an underwriter at the start of the review, instead of sending them down five different Google searches and, you know, researching. And there's some key things you can identify using the analytics. You can figure out what are your most frequently asked questions?
What are your business drivers? What is your underwriting talent? What are they looking at that maybe no one else is looking at that you think is giving you an edge? And then how do you package that and provide that to the underwriters so that they can then make informed decisions faster? I think it's a lot more about scaling than actually reducing, you know, your staff, right? It's not about really cutting to the bottom line. But if you've worked the desk as an agent, then you understand that once you get somebody on the phone willing to talk to you, willing to give you their payroll information, and you need to be able to return to them an answer before they lose interest.
And we've had this process of back and forth, especially in workers' compensation underwriting and these mammoth lists of questions. And, you know, it's really frustrating from a sales perspective. And you want to, you know, I say we're in the business of paying benefits. We are. Our other two values is that we protect wealth and we help people build wealth. We're helping our agents build wealth and we're helping our clients protect their wealth in their businesses. And so you have to be good at those two things, too.
And analytics helps us and AI helps us refine these processes so that we can deliver them in a much better way to our end users.
Rob Galbraithyeah i think some of the consensus was um definitely automating you know as much as possible but more of the data gathering steps to your point right um a lot of talk about underwriting workbenches and bringing all the information whether that be internal whether that be external right it could be a department of transportation report it could be you know loss runs whatever it is right and then actually doing maybe some proprietary you know risk scoring or things like that. But all that information is presented to the underwriter.
So they're actually using their underwriting skills and training, right? Rather than data gathering, which unfortunately was a lot of the job in the past where, yeah, they knew where to look, they know what to get, but you know, that information gathering isn't, that's not where they're adding the most value, right? They're adding the most value is once they have it, right their insights their judgment uh those conversations with the agent or broker you know um it's it's that part that's really the special sauce of an underwriter like what they're really bringing the value add it's not logging into you know and we would use um the past i've used tools like rpa or whatnot but then as soon as like the you know driver's license website changes and whatever all of a sudden your rpa breaks and you gotta you know and so there was definitely some frustrating and i remember um you know executive just saying hey i still have people that's taking information from screen one and having to type it into screen two because these you know systems like don't talk to each other so they're very sometimes basic prosaic problems that you know did we hear the hype right but sometimes the day-to-day life like there's a lot of area for incremental improvement
Carrie Coronadooh well yeah i i think there's a lot of low-hanging fruit especially in insurance. I mean, even still, I've been in the InsurTech space, at least as a witness for, you know, 15 years. And I've been, I did not go this year, my operations director did, but I also attend ITC and I see, I've seen the movement. But we still move very slow as an industry, insurance does. And so I still see a lot of low hanging fruit, even in my own organization that we're working on right now, but just throughout an opportunity to, um, learn from each other and share information without giving away our secret sauce, you know, that makes all of us, uh, better.
Um, I think that if, if you've ever worked an underwriting desk and have received 60 pages of loss runs, you will know how beneficial it is to have a program that can read that information, transcribe it into Excel, give you data points that you may not have recognized or would have taken you four, five, six hours of scanning to see like, oh, out of these 175 claims, what percentage are cumulative trauma okay now you've got it i remember tacking one two three four line through right sitting at a desk and those would be my notes and now to just run that through a program and have that delivered i think it's really great my concern which i think exists across the industry is that i know to tell the ai to do that because it's the job that i did And so as we move and move through this AI, are we going to get to the point where it's always just answering itself and we're not really getting new insights or, you know, we should be, these should be learning models, but we have to understand at what speed should they be learning?
And like, to your point earlier, just like a human, okay, if we have this one severity exposure, does the model now decide, well, we shouldn't write anything that has zip lines. And so now our whole camp program is gone because we, because the model learned something and we're not maybe confident in what it's learned. Right. So there's a, there's going to be a lot of managing the bots that I don't think we're having enough kind of respect for yet because we are starting with the most low-hanging fruit and processes that we've been doing for hundreds of years in the insurance industry.
We've got a lot of data points for that, but what about what we want to do that's new and how are we going to teach the tech to do that?
Rob GalbraithSo following up on that point and kind of tying back to your earlier comment about the conversation you were having with a more seasoned underwriter about how their job will evolve so um a lot of conversation uh in my circles about talent and what's happening with talent and i i think everyone you know still agrees we need a human in the loop etc but i think there is a concern about you know underwriting has been such an apprenticeship job over the years and you kind of learn right and you start as a ua and you kind of work your way up and and you know your um level of responsibility you know keeps increasing increasing and so if we start automating or simplifying you know those the more routine tasks or whatnot you know do we it's already been a challenge of you know a lot of people don't stay at the same company every 30 you know for 30 years the way that they used to and to career ladder has naturally kind of a career journey and so there's a little bit of like robbing peter to pay paul like in the industry right because you're trying to um recruit more seasoned probably underwriters right as you know the retirement wave has hit or whatnot but i think there's a lot of concern about the entry level that first five to 10 year kind of role and are we creating a gap there so i don't know if you just i'll throw it broadly to you like from a talent perspective how do you see this maybe playing out of the next five to ten years
Carrie Coronadoyeah i i remember the first time we eliminated file clerks and went to to um paperless right and thinking like well how will anybody ever start in our business if they can't do like certs. Like if you're not doing certificates of insurance and you're not filing and you're not seeing the documents, you know, the way that when I was coming up, if, if, if something came in and I was curious about it, I would just go to the underwriter or to a leader and say, Hey, I've never seen this form before.
What does this do. And so it's also was, it's always been a way, um, to vet out curiosity, which is a really important part of underwriting. And so, um, I don't, I don't completely know the answer. I know I, I tell my team, I've never done this before either. So let's figure it out together. Um, And I'm working on really kind of an associate underwriter accelerated path to underwriting that starts as somewhat of an assistant position and is responsible for monitoring really the tech, but also beginning early renewal underwriting and that kind of stuff.
I hope it works. But in my office, I have a black and white picture of a typing pool from, you know, the 40s, I think. And it just reminds me all the time that all of that exists just inside of my tablet. So it's we evolve. Right. But people are still working. I think there was a time that we were scared that we wouldn't without typing pools, we wouldn't be able to employ people. So, you know, we've, we've learned as we've gone on and there's, I remember hearing something at a conference of some years ago that, you know, 40 % or something of the jobs that were going to be had in 12 years didn't exist yet.
But wow, you know, I think we're at a precipice of that again. So just, we have to evolve, I guess that's the best way to say it.
Rob GalbraithYeah, I love that. know and and um yeah it's not fully clear right but you're actively working towards shaping the paths and i love that you're bringing your team with you along that journey carry so um just to wrap up you know this has been a fantastic conversation really enjoyed your insights so kind of looking ahead how do you see workers compensation underwriting evolving over the next five to year five to ten years is data ai automation continue to mature and what should carriers and underwriting leaders be doing today to help prepare for that future?
Carrie CoronadoI am very interested in video AI and kind of how that's going to change our clients' lives and therefore our ability to understand them, underwrite them. I think, I mean, video AI can look at so many clips so much more minute detail than any human eye can. So if I'm insuring like currently in skilled nursing facilities, for example, video AI has the opportunity to show us that somebody's gait has changed and the likelihood of them falling has increased just in a micro way that we can't see with the human eye.
It can review manufacturing processes the same way there's just so much i think information in in video visual that we're yet to to really capture and i think that finding a way to continue to reward businesses that are best in class we'll be able to better identify that by having visual proof and the data points to say yes they don't just say that they stretch for 15 minutes every three hours you can see it maybe there's a body mechanics measurement or a video measurement or something along those lines that really can validate what what good mitigation tactics are and and then we have to ask ourselves is stretching working because we've been saying that for the last 20 years but can can we test that theory with some of these newer tools and devices.
I think we can and we will. So I think it's going to be being open to that in industries, understanding that risk profiles will be changing And what opportunities will we find in those changes? There are, I think, competing personalities in terms of tech adoption. It's funny, we talk a lot about the more seasoned or veteran employees and their distrust in technology or they're not wanting to. What we don't talk a lot about is some of the people who have had tech their whole lives that are coming into the industry and anticipating instant gratification or for things to work the way their bank app works or, you know, these different, the appetites are so different on each side.
And there's not a right answer for either. Right. We don't want to be so dependent on tech that we lose sight of humans and and doing good and capacity and all of those things. I find myself a lot reminding my team that we insure people and these are real businesses. They're not just numbers in a spreadsheet. So that's going to be part of that challenge, too, is, you know, adoption without blinders.
Rob GalbraithYeah, I love that. I wish I could remember where I saw this article and I'm probably misremembering part of it. but it was, I want to say it was like a Wall Street investment bank was saying that they had hired a bunch of young people that were experts in AI, right? The cutting edge developments. And they were finding that they had to introduce new training and supplement that they thought they would be like really good employees. But it turns out that they felt like their critical thinking skills were really poor relative to prior generations, you know, because they hadn't been faced with they've been so used to kind of you know defaulting to whatever the the machine told them or whatnot that's just some of the healthy skepticism of putting things in context was was really lacking right and so i i think about that particularly in an underwriting context like okay yeah i think this is gonna um the the the really the human machine relationship is gonna continue to evolve over time but i i don't think we're at a point in the even five to ten years right or they're going to just be able to fully take over for us
Carrie Coronadoso well i think it goes back to kind of where what my for me right now i will continue to stay uh people-centric like i like i said and i think if you do that and you validate people and especially younger people or maybe not younger let's just say tech forward people or people who spend a lot of time with technology um keep telling them that they're special and important and seen and heard and that you don't always default to the machine that they have a voice and they can challenge that and they can come to me or someone else on the team and say hey this doesn't seem right just because they the computer says it's right doesn't feel right to me if you create that kind of space i think that validates people, um, you'll have better results, uh, in this, in this whole kind of process of applying these new technologies to your businesses.
Rob GalbraithCarrie, this has been a fantastic conversation. I really appreciate your insights. So many good nuggets from, uh, our talk today. If there are folks, um, that are watching or listening to us out there and they want to reach out, maybe they have got a question for you or want to compare notes. What's the best way for them to connect with you?
Carrie CoronadoI think LinkedIn is great. And it's just Carrie Coronado, Care West Insurance. So I'm easy to find.
Rob GalbraithFantastic. Well, thank you so much, Carrie. Really appreciate you being on the InsurTech Geek podcast. And thank you, audience, for once again, tuning in today to geek out for our interview with Carrie Coronado from Care West Insurance. We'll see you next time.
Carrie CoronadoThanks, Rob.